FO Research
The Record
Every Financial Oracle call, dated before the data and scored against the tape. 80 calls, 76% held or better, every miss shown.
The Record · scored to 9 October 2026 · revised 13 October 2026
Dated before the data. Scored after it.
80 calls. 76% held or better. Every miss is on this page, and every number links to the note that made it.
Held includes 1 two-branch call scored Branch resolved. Partials count inside held or better and are shown separately; held alone is 47/80 (58.8%). Also on the record: 2 early, 1 ambiguous, 3 new and not yet scored, 1 trigger not met (shown, not scored). Late deliveries sit in the process log, not in the call count.
The calls that paid the most
Peak and now are both shown. Entries and exits are the reader's own.
The spine · our highest-conviction macro calls
Long dollar. No cuts. The floor holds.
One line per call; open any line for the reasoning and the path. Each is held from its entry to the 9 October close and marked while its thesis stands; none has hit its stated invalidation. These are marks on open calls, kept outside the scored count below.
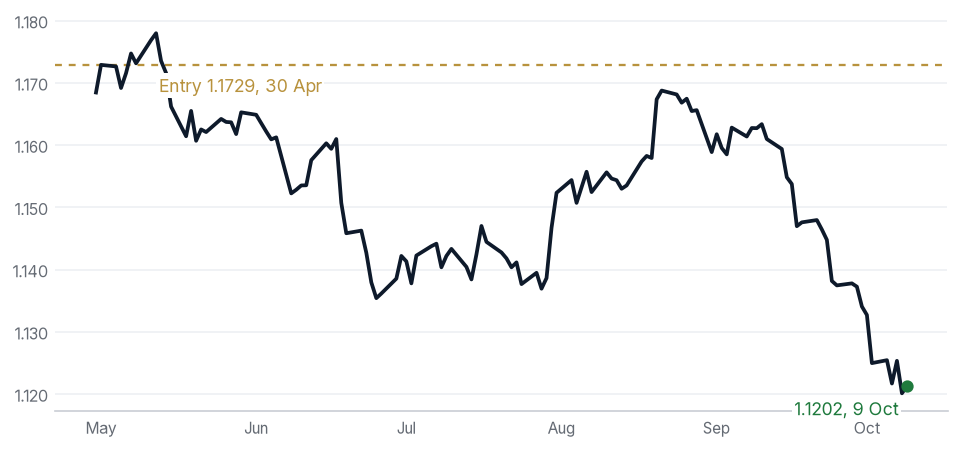
Short EUR/USD30 Apr1.1729 → 1.1202+527 pips (peak +533 pips)✓ Held · ○ Open
The founding dollar-regime call: sell EUR rallies while US rate differentials and a constrained Fed keep the dollar bid. It gave most of the June move back through August, recovered it in September as the Fed moved first, and set a new peak on 7 October at 1.1196 as the long bond closed at its highest since 2002, with speculators carrying a record gross euro short into the move.
Read the note: Stronger for Longer · the dollar-regime call
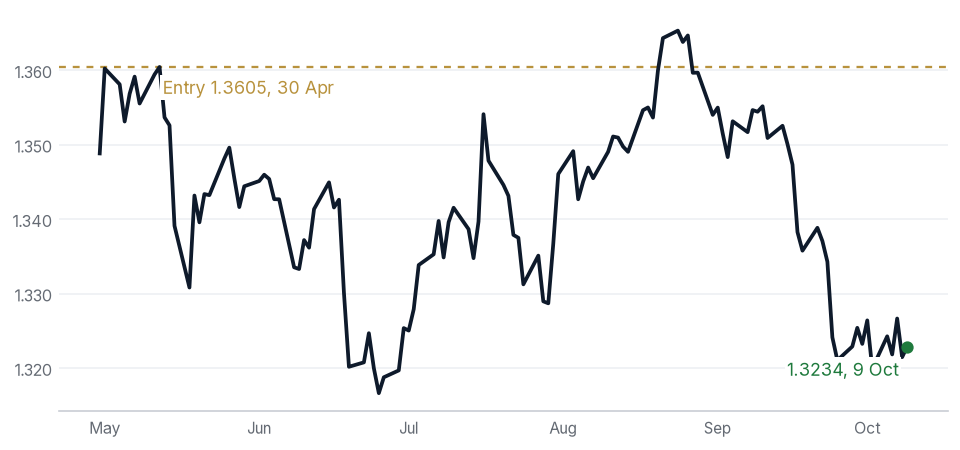
Short GBP/USD30 Apr1.3605 → 1.3234+371 pips (peak +441 pips)✓ Held · ○ Open
GBP upside capped while the dollar stays bid and the Bank of England lags the Fed. The Bank held 6 to 3 on 17 September while the Fed rose 12 to 0: the lag the note described, on the record.
Read the note: Stronger for Longer · the dollar-regime call
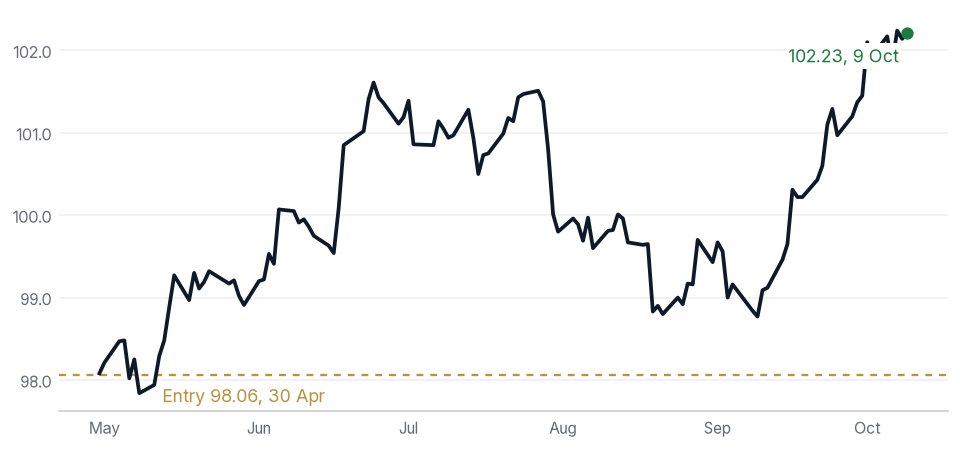
Long the dollar (DXY)30 Apr98.06 → 102.23+4.3% (peak +4.3%)✓ Held · ○ Open
The dollar broadly higher for longer on rate differentials and US relative strength. A new peak on 7 October at 102.25, through the June high, as the long bond closed at its highest since 2002.
Read the note: Stronger for Longer · the dollar-regime call
Short AUD/USD30 Apr0.7201 → 0.6984+217 pips (peak +314 pips)✓ Held · ○ Open
Fade AUD rallies into broad dollar strength while China momentum stays soft.
Read the note: Stronger for Longer · the dollar-regime call
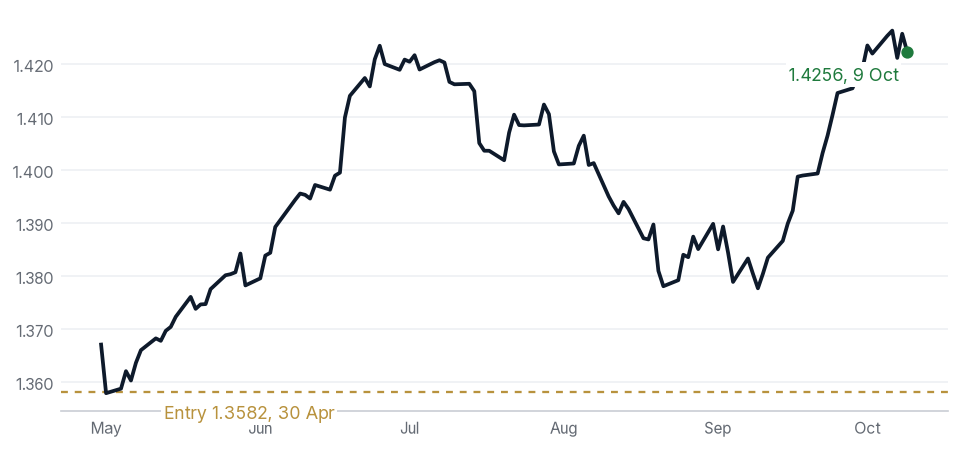
Long USD/CAD30 Apr1.3582 → 1.4256+674 pips (peak +678 pips)✓ Held · ○ Open
USD/CAD higher on the oil and yield-spread divergence and a price-defence regime. A new peak on 5 October at 1.4260; four pips under it at the as-of date.
Read the note: Stronger for Longer · the dollar-regime call
Short NZD/USD28 Apr0.5886 → 0.5612+274 pips (peak +287 pips)✓ Held · ○ Open
NZD bearish while USD momentum and risk-off flows persist. The note was published as a 1 to 2 week tactical read, and at the end of that window (12 May) the pair was 79 pips above entry. The same bias was carried into the dollar regime by later notes: Stronger for Longer (30 April) on AUD and NZD, the 19 June Brief (short NZD up 52) and the 6 October Premium (AUD and NZD lower with the euro). Marked while that thesis stands, as every spine call is: 0.5612 at the 9 October close, a new peak on 7 October.
Read the note: Dollar, Oil, Higher for Longer · the dollar, oil and rates regime call
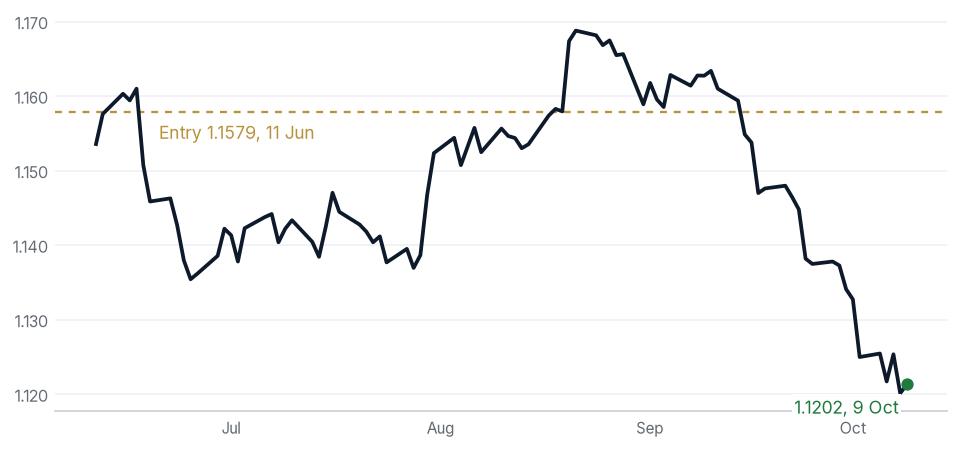
Short EUR/USD11 Jun1.1579 → 1.1202+377 pips (peak +383 pips)✓ Held · ○ Open
EUR sold even on the ECB hike: tightening into a downgraded growth outlook is not a strong-currency story. The note set no horizon or invalidation of its own and framed the read inside the 30 April regime call, whose invalidation (a decisive Fed pivot to easing) has not fired; no later note closed it. The ECB rose again on 10 September and the euro fell anyway; a new peak on 7 October.
Read the note: Both Sides. One Tell. · PPI and ECB, the dollar winner
Short GBP/USD15 Jun1.3450 → 1.3234+216 pips (peak +286 pips)✓ Held · ○ Open
GBP soft into Warsh's hawkish hold and a firmer dollar. The note set no horizon or invalidation of its own and named the regime as stronger for longer; the 19 June Brief scored its base case as printed, and the 12 October Brief still marks the regime held with sterling at 1.3234. Offside through August; back in profit when the hold became a rise.
Read the note: New Chair. Same Floor. · the Warsh FOMC preview
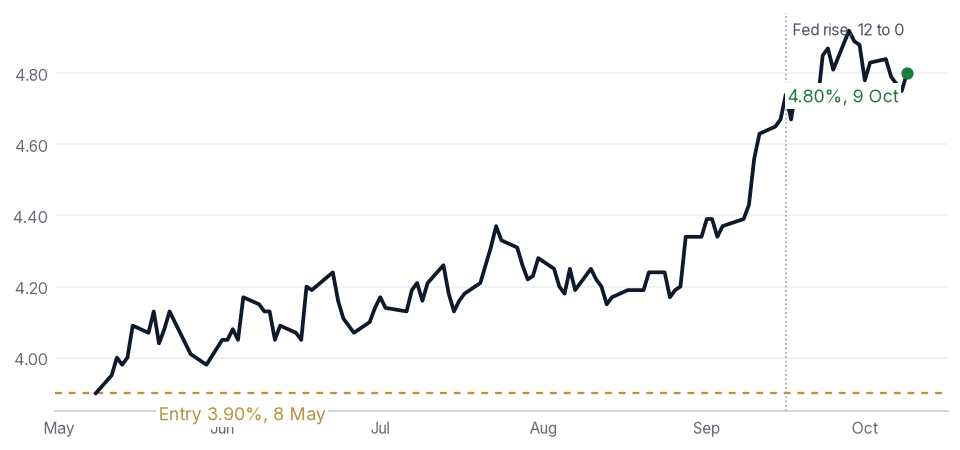
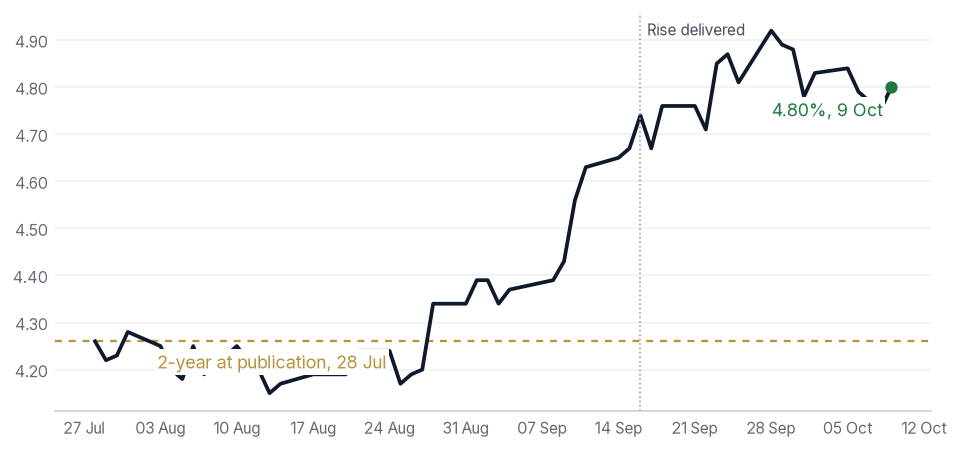
No cuts (US 2-year)8 May3.90% → 4.80%+90bp (peak +102bp)✓ Held · ○ Open
The Fed cannot ease into a 4-handle inflation backdrop: the front end stays anchored and cut bets get priced out. They were, and then some: the committee raised the range to 3.75 to 4.00 on 16 September, 12 to 0, and the two-year held 4.80 through a payroll print of 29,000 on 2 October even as the strip took the October rise down to one chance in five, then closed 4.80 again on 9 October after dipping to 4.75 into the minutes.
Read the note: The Long Bond Disconnect · term premium owns the long end
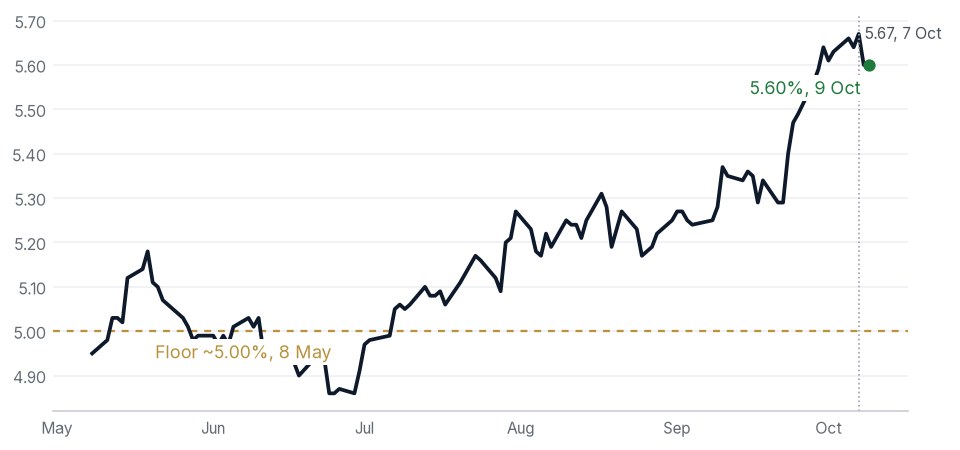
The 30-year floor holds8 May to 16 Jun~5.00% → 5.60%+60bp (peak +67bp)✓ Held · ○ Open
Term premium and the deficit hold the long-end floor through every test: a hot jobs print, a soft CPI, a new chair, a ceasefire and its expiry, an enlarged issuer bid, a unanimous rise, a payroll print of 29,000 that could not move it and a $22bn thirty-year reopening that cleared at 5.618 with the long end closing lower on the day. It ran to 5.31 on 17 August, eased when the Treasury doubled its buybacks, went to 5.67 on 7 October, the highest close since July 2002, and closed 5.60 on 9 October with the breakeven at 2.33: the entire move and more was real yield.
Read the note: The Floor / Floor Held / Buyers · the rate-floor thesis
* FX total: seven calls held from entry to the 9 October close (Short EUR/USD 30 Apr +527, Short GBP/USD 30 Apr +371, Short AUD/USD 30 Apr +217, Long USD/CAD 30 Apr +674, Short NZD/USD 28 Apr +274, Short EUR/USD 11 Jun +377, Short GBP/USD 15 Jun +216), all in profit; the peak total was +2,922. Entries are the published levels; each traded after publication. USD/JPY rows are level calls with no pip scoring.
The full record · every stated cross-asset bias
The complete scorecard, grouped by theme
One line per call. Open a theme to see its rows; open a row for the note's own wording and the path. Unless flagged tactical, calls carry a multi-quarter horizon and stay open until their stated invalidation fires or their horizon passes.
Rates30 scored · 23 held · 2 partial · 5 missed · 83% held or better
The 30-year floor and its ranges21 scored · 18 held · 3 missed · 86% held or better
✓ HeldUS 30-yearSix Pillars · 1 Jun~5.00 → 5.60○ Open
The 30-year stays pinned near 5.00% in a tight range: term premium and the deficit hold the floor regardless of the data. The floor held and the range did not: 5.31 in August, eased on the 19 August buyback expansion, then 5.67 on 7 October, the highest close since 2002.
Read the note: Six Pillars · the structural-regime read
✓ HeldUS 30-yearHeld Out for the IPOs · 9 Jun5.01 → 5.60○ Open
The 30-year holds 5.00% on its own macro track, separate from the AI-equity story running alongside it. It has, by 56 basis points, while the Nasdaq went nowhere.
Read the note: Held Out for the IPOs · the AI valuation and IPO read
✓ HeldUS 30-yearThe Floor Held. Again. · 10 Jun5.03 → 5.60○ Open
The 30-year holds its floor through the CPI print: the floor is structural, not data-driven. It ran through the 5.15 top of the stated band to 5.31 in August and 5.67 by 7 October, the highest close since 2002, through three more CPI prints and a rise.
Read the note: The Floor Held. Again. · the post-CPI rate-floor verdict
✓ HeldUS 30-yearThe Buyers Go Home. · 16 Jun4.93 → 5.60○ Open
The 30-year holds even as the war premium drains: the floor is the vanishing bid, not the conflict. The conflict came back, the bid did not, and the issuer's own enlarged operations have not held the line either: 5.60 at the 9 October close, after 5.67 on 7 October, with the Treasury filling its ceiling at one enlarged operation in four.
Read the note: The Buyers Go Home. · the vanishing-bid thesis
✓ HeldUS 30-yearThe Bid Comes Home · 23 Jun4.94 → 5.60○ Open
As the foreign official bid fades, the marginal buyer of American duration turns domestic. The direction held and the buyer arrived closer to home than the note wrote: on 19 August the issuer itself doubled its long-end buybacks, and by 1 October was filling its ceiling at one enlarged operation in four while the long end went to 5.67 on 7 October regardless.
Read the note: The Bid Comes Home · the domestic bid returns to the long end
✓ HeldUS 30-yearThe Pipeline Translated · 25 Jun4.86 → 5.60○ Open
Supply-side inflation is global, giving every hawkish committee the same cover and holding the long-end floor. Japanese ten-year yields reached 3.055% on 24 September, the highest since 1996; gilts and bunds at multi-year highs.
Read the note: The Pipeline Translated · supply-side inflation goes global
✓ HeldUS 30-yearThe Crack Arrives. The Floor Holds. · 2 Jul4.98 → 5.60○ Open
The energy shock reaches the consumer through refining, and the long end does not soften into it. August CPI printed +0.4 on gasoline and the long end went 21bp higher in the fortnight after.
Read the note: The Crack Arrives. The Floor Holds. · the refining channel opens
✓ HeldUS 30-yearThe Synchronised Floor · 10 Jul5.06 → 5.60○ Open
The floor is a cross-central-bank regime, not a US story: Fed and ECB turn hawkish together and duration stays offered. In September the Fed rose 12 to 0, the ECB rose, the Bank of Japan went to 1.25 on 7 to 2 and the Bank of England held 6 to 3 with three votes for a rise. The synchronised floor became a synchronised repricing.
Read the note: The Synchronised Floor · Fed and ECB hawkish together
✓ HeldUS 30-yearThe Rebuild Begins. The Floor Hardens. · 10 Jul5.06 → 5.60○ Open
Term premium rebuilds rather than fades, hardening the floor from below. The ten-year breakeven fell from 2.38 to 2.34 across the rise while the real ten-year went from 2.55 to 2.90: the whole September move was term premium and real yield, not inflation compensation.
Read the note: The Rebuild Begins. The Floor Hardens. · the floor hardens on supply
✓ HeldUS 30-yearThe Disinflation Arrives. · 15 Jul5.08 → 5.60○ Open
A soft June CPI bends the floor without breaking it: a bull steepener, not a broad rally.
Read the note: The Disinflation Arrives. · soft CPI, unbroken floor
✓ HeldUS 30-yearThe Crack Premium · 21 Jul5.13 → 5.60○ Open
Refining margins, not crude, carry the shock into headline inflation and keep the long end pinned high. The August print carried it as written, +0.4 with gasoline +3.9%.
Read the note: The Crack Premium · refining, not crude, is the channel
✓ HeldUS 30-yearThe Shock Round-Trips. · 27 Jul5.12 → 5.60○ Open
Crude round-trips in four sessions and the long end keeps its level: the fades do not undo the ratchet. Brent has since run to 106 and back to 98; the long end kept none of the fades.
Read the note: The Shock Round-Trips. · the round-trip experiment
✓ HeldUS 30-yearThe Ratchet · 28 Jul5.09 → 5.60● Resolved
Each supply shock leaves the stance tighter than it found it while the fades leave it alone, and the next move is a rise, not a cut. Delivered on 16 September, 12 to 0, the first rise since 2023. Resolved.
Read the note: The Ratchet · shocks ratchet the stance tighter
✓ HeldUS 30-yearThe Fed Held. The Hawks Didn't. · 30 Jul5.21 → 5.60○ Open
A hold with three dissents for a rise keeps the long end elevated. The dissents became the decision seven weeks later.
Read the note: The Fed Held. The Hawks Didn't. · the three-dissent hold
✓ HeldUS 30-yearSeven Dissents. One Direction. · 3 Aug5.23 → 5.60○ Open
Seven hikes voted across three committees, none for cuts, and the long end holds its new range. It ran to 5.31, eased below the publish level on the buyback doubling, then went to 5.56 as the votes became decisions: the Fed 12 to 0 for a rise, the Bank of Japan 7 to 2.
Read the note: Seven Dissents. One Direction. · seven hikes voted, none for cuts
✗ MissedUS 30-yearThe High-Water Mark · 18 Aug5.28 → 5.60○ Open
The tightening migrated from the committee to the curve, and the published 4.85 to 5.20 band was retired for 5.05 to 5.45, with a pre-commitment that a close through the top would be scored as a range miss on the day it printed. Twenty-six consecutive closes settled inside it, 5.17 to 5.40. The twenty-seventh closed 5.47 on 24 September and 28 September closed 5.56, eleven basis points above the line. The mechanism is not what failed; the level did, and it is scored as the note said it would be.
Read the note: The High-Water Mark · the band redrawn, the miss scored
✓ HeldUS 30-yearTen Dollars Offered. One Accepted. · 20 Aug5.23 → 5.60○ Open
The buyback doubling read as signal, not flow: the issuer smooths the ink it will not stop writing, and rallies under its bid are distortion, not discovery. No rally came. The issuer has taken its ceiling at each enlarged operation since 9 September and the long end went to 5.56 regardless. The note's separate queue claim is scored in the pre-registered tests below.
Read the note: Ten Dollars Offered. One Accepted. · the issuer's bid as signal, not flow
✓ HeldUS 30-yearThree Hands. One Pen. · 25 Aug5.17 → 5.60○ Open
The issuer test, standing from 18 and 20 August: long-end rallies on the issuer's own bid are distortion, not discovery, and the witnesses that testify unaided are the two-year and gold. Both witnesses spoke through September: the two-year led the committee into a rise and gold fell through 4,449 as it did.
Read the note: Three Hands. One Pen. · the issuer test and its witnesses
✗ MissedUS 30-yearThe Tide Line · 14 Sep5.34 → 5.60○ Open
Base case: the upper half of 5.05 to 5.45, the pivot beneath, auctions absorbed after concessions. The upper half held for eight sessions, then the band broke at 5.47 on 24 September and 5.56 on the 28th, the range miss the note pre-committed to. The concessions came and the auctions were absorbed badly: the 20-year stopped at 5.42, the 5-year at 5.033 on a 2.21 cover, the weakest since 2025.
Read the note: The Tide Line · the reweight, scored on the print
✗ MissedUS 30-yearThe Tide Line · 14 Sep5.37 → 5.60○ Open
The scenario map said a close through 5.45 moves weight to Path C, the inflation path. It fired on 24 September with the breakeven falling, and the 6 October Premium overrode it, cutting Path C to 20 because the move was term premium rather than inflation. Scored against the desk's wording, not the tape: the trigger should have carried a breakeven condition.
Read the note: The Tide Line · the reweight, scored on the print
✓ HeldUS 30-yearThe Price of Duration · 6 Oct5.63 → 5.60○ Open
Operating range 5.30 to 5.80 with the retired 5.45 as the pivot; a close through either edge is a range miss scored the day it prints, and the floor thesis keeps its own 4.85 falsification. Registered at 5.63 on the 2 October settle. The first full week printed 5.66, 5.64, 5.67, 5.60 and 5.60 (Treasury par curve, 5 to 9 October 2026), inside the range in its upper half with a new high on Wednesday: held for the week, as the 12 October Brief scores it, and open.
Read the note: The Price of Duration · the regime named, the range redrawn, the reweight on the fired tell
The 2-year and the no-cuts call4 scored · 2 held · 1 partial · 1 missed · 75% held or better
✓ HeldUS 2-yearThe Floor Held. Again. · 10 Jun4.13 → 4.80○ Open
The 2-year stays anchored with cut pricing capped: the Fed cannot ease into a 4%-handle inflation backdrop. It could not. The committee raised on 16 September, 12 to 0, and the two-year closed 4.80 on 9 October after 4.92 on 28 September.
Read the note: The Floor Held. Again. · the post-CPI rate-floor verdict
✓ HeldUS 2-yearThe Buyers Go Home. · 16 Jun4.05 → 4.80○ Open
The 2-year holds with no cuts priced into Warsh's first meeting: the constrained stance carries to the new chair. It carried to his third meeting, which delivered a rise.
Read the note: The Buyers Go Home. · the vanishing-bid thesis
✗ MissedUS 2-yearSix Pillars · 1 Jun~4.0 → 4.80○ Open
The 2-year drifts in the high-3s as the market waits on a Fed on hold. It repriced to a 4-handle and then to 4.92 as a rise was delivered instead: the no-cuts umbrella was right, this level call was not, by nearly a point.
Read the note: Six Pillars · the structural-regime read
~ PartialUS 2-yearThe Tide Line · 14 Sep4.65 → 4.80○ Open
Holds 4.50 to 4.75 as the rise lands; the committee's tenor fully priced. It went through the top to 4.92 as a second rise for October priced near seventy per cent: the direction and the mechanism held, the band did not.
Read the note: The Tide Line · the reweight, scored on the print
Curve and breakevens5 scored · 3 held · 1 partial · 1 missed · 80% held or better
✓ Held2s30sThe Floor Held. Again. · 10 Jun+90 → +80bp○ Open
The 2s30s curve stays steep, a market pricing structural supply at the long end while the front waits on the Fed. It steepened to a 108bp extreme in August, bear-flattened to 53bp on 21 September as the front end led the committee into a rise, and re-steepened to 80 by 2 October as the strip took October down to one chance in five and the long end went further: the front end is waiting on the Fed again and the long end is pricing supply. Ten basis points flatter than at entry, on the mechanism the call described.
Read the note: The Floor Held. Again. · the post-CPI rate-floor verdict
✓ Held2s30sThe Buyers Go Home. · 16 Jun+88 → +80bp○ Open
The 2s30s curve holds steep, the shape of a bid problem at the long end. The bid problem is now visible in the issuer's own operations, $46bn offered into a $6bn buyback on 1 October, and the curve re-steepened to 80 as the front end fell on a weak payroll and the long end did not.
Read the note: The Buyers Go Home. · the vanishing-bid thesis
✗ Missed ⇆Sept hike pricingSeven Dissents. One Direction. · 3 Aug66% → ~50% → delivered● Resolved
The pre-registered test, quoted as published: hold above half through benign data and the ratchet is priced. It did not hold. Pricing settled below half at three consecutive post-CPI sessions and the desk wrote the reversal note it had pre-committed to. It then re-armed to near 90% on the August CPI and the rise was delivered on 16 September, 12 to 0. The direction the note argued arrived six weeks later; the test it registered failed on its own terms, and the miss stands as scored.
Read the note: Seven Dissents. One Direction. · seven hikes voted, none for cuts
~ Partial2s30sThe Tide Line · 14 Sep+69 → +80bp○ Open
Flattens further, the migration's bear flattener. It did, 69 to 53bp on 21 September, then re-steepened to 80 by the 9 October close on term premium as the long end went further without the committee. Eleven basis points steeper than at entry; the flattener the note described has been a steepener since the 23rd.
Read the note: The Tide Line · the reweight, scored on the print
✓ Held10-year breakevenThe Tide Line · 14 Sep2.36 → 2.33○ Open
2.30 to 2.45, the three-month high held. Inside the band throughout, 2.31 to 2.40, and falling into the rise: 2.38 on the eve of the decision, 2.34 on 28 September and 2.33 on 9 October. The credibility the committee bought is priced here, and it is why the desk reads the long-end move as term premium rather than a pass-through.
Read the note: The Tide Line · the reweight, scored on the print
Fed and pre-registered tests15 scored · 8 held · 3 partial · 3 missed · 1 ambiguous · 73% held or better
✗ Missed ⇆The keynoteThree Hands. One Pen. · 25 Aug~36% → ~50%● Resolved
The desk expected continuity and registered the risk branch: conditions named insufficient, progress named stalled, the front end leading, September toward the coin flip. The risk branch fired nearly verbatim and the desk scored itself missed at full weight, the miss first, in The Chair Speaks. The Pen Stays.
Read the note: Three Hands. One Pen. · the issuer test and its witnesses · alternate pre-registered
✓ HeldThe benchmark revisionThree Hands. One Pen. · 25 Aug-79k● Resolved
Registered: a revision under roughly 300,000 disarms the collision's second hand and leaves the keynote alone on the stage. It printed minus 79,000 against a consensus near plus 183,000, and the session traded entirely on the speech.
Read the note: Three Hands. One Pen. · the issuer test and its witnesses
✓ HeldJuly core PCEThree Hands. One Pen. · 25 Aug0.2 / 3.3● Resolved
Registered: an in-line print changes nothing, because the desk's dated inflation test is the 11 September CPI. It printed 0.2 on the month and 3.3 on the year, in line. Nothing changed.
Read the note: Three Hands. One Pen. · the issuer test and its witnesses
✓ HeldBank of KoreaThree Hands. One Pen. · 25 Aug2.75 → 3.00● Resolved
Registered: a second rise to 3.00% extends the synchronised floor by another jurisdiction. It printed 25 basis points to 3.00, back to back, one dissent, framed by the governor as pre-emptive.
Read the note: Three Hands. One Pen. · the issuer test and its witnesses
✓ HeldThe printJuly Never Happened. September Re-Arms. · 7 Sep70% → ~90%● Resolved
Marked 60 / 20 / 20 on the labour leg and held the formal reweight for the print: a hot August CPI seals the rise, a cool one with the crack still wide earns nothing. It printed hot, +0.4 with gasoline +3.9%, and sealed it: near 70% on the eve, nearly 90% on the release tick, with the dollar flat and the long end down. The asymmetry printed as written.
Read the note: July Never Happened. September Re-Arms. · the labour leg re-arms the rise
~ PartialThe migrationThe Issuer Offered Six. The Market Sold It. · 11 Sep2Y 4.63 → 4.92 · 30Y 5.35 → 5.56○ Open
A two-year that keeps rising into the print while the long end stalls is the migration, and 5.45 holds. The two-year kept rising, 4.63 to 4.92; the long end did not stall, it went to 5.56 through the 5.45 the note called unbroken. Half the read held and the half that was a level did not.
Read the note: The Issuer Offered Six. The Market Sold It. · the migration into the print
✓ HeldThe voteThe Tide Line · 14 Sep→ 12 to 0● Resolved
A rise with two dissents or fewer confirms the committee has joined the curve. It printed 12 to 0, the first rise since 2023, to a 3.75 to 4.00 range.
Read the note: The Tide Line · the reweight, scored on the print
✓ HeldThe statement and the dotsThe Tide Line · 14 Sep→ 4.1 / 4.1● Resolved
One further rise beside the delivered one matches the strip, with the energy clause named as the thing to watch. The median carried exactly one, 4.1% for 2026 and 4.1% for 2027, a plateau not a cycle, and the energy language was deleted.
Read the note: The Tide Line · the reweight, scored on the print
? AmbiguousThe curve by the Thursday settleThe Tide Line · 14 Sep69 → 62 → 80bp● Resolved
Registered as a rise that flattens, the two-year up more than the thirty-year or the long bond lower but inside 5.05. Ambiguous as published, and the desk does not resolve its own ambiguity in its own favour. On the owed settle the long bond was lower at 5.29 but nowhere near 5.05, and 2s30s widened a basis point, 61 to 62. Over the fuller window the flattening arrived, to 53bp on 21 September, then reversed to 80 by the 9 October close. The wording is the desk's fault.
Read the note: The Tide Line · the reweight, scored on the print
✗ MissedThe chair on the pressureThe Tide Line · 14 Sep4.74 → 4.67 on the owed settle● Resolved
Registered verbatim: not the words, which the desk does not score, but whether the front end holds the rise through the press conference. The two-year went 4.67 to 4.74 on the decision and back to 4.67 at the 17 September settle. It gave back the day's rise exactly, on the settle the test was owed on. The front end has since gone to 4.92; the test was written to be scored on the owed settle and it is scored there.
Read the note: The Tide Line · the reweight, scored on the print
✓ HeldThe buyback queueTen Dollars Offered. One Accepted. · 20 Aug$19.9bn → $46.4bn○ Open
Built on a single number, $19.868bn of offers against a $2bn door in the 20 to 30 year sector, and registered the test in dollars. Three operations near ten billion followed and the desk retired the claim on 29 September. On 1 October the 10 to 20 year operation drew $46.391bn against a $6bn maximum, 7.7 times the door, the full $6bn taken in two of 41 issues at 67.398 and 75.976. The August claim stands in its original form: the queue was waiting for the price. The retirement is scored as the desk's miss in the row below. The retest on 8 October in the measured sector drew $14.886bn against $6bn, between the two pre-registered reads: partial, scored in its own row.
Read the note: Ten Dollars Offered. One Accepted. · the issuer's bid as signal, not flow
✓ HeldThe 2 October payrollsTwelve to Nothing · 29 Sep4.78 → 4.83 vs 4.80● Resolved
Registered before the print: a two-year that holds 4.80 through it says the second rise is real; through 4.65 says the strip got ahead. The print was 29,000; the two-year went in at 4.78, below the line, and settled 4.83, above it (Treasury, 1 and 2 October 2026). Held on the settle the test was written for, with the strip cutting October to one chance in five the same afternoon, which the scoring note says beside the result.
Read the note: Twelve to Nothing · the FOMC tests scored; the curve went further
✗ MissedThe 1 October buybackTwelve to Nothing · 29 Sep$46.4bn vs the $20bn line● Resolved
The first 10 to 20 year operation since the queue claim was retired: offers near $20bn would say the desk retired it too early. It drew $46.391bn against a $6bn door (TreasuryDirect, 1 October 2026). The retirement was the desk's miss, scored at full weight in the 5 October Brief; the August thesis is reinstated above.
Read the note: Twelve to Nothing · the FOMC tests scored; the curve went further
◆ NewBreakevens, the discriminatorTwelve to Nothing · 29 Sep2.34 → 2.33 vs 2.50○ Open
Inflation compensation falling while nominal yields rise reads as term premium and supply, not an expectations shock. Through May's 2.50 high, the story becomes a credibility problem and the map changes with it. 2.33 at the 9 October close, down three on the week while December Brent rose from 100.20 to 104.72 and the long end set a new high: supply, not pass-through, and moving away from 2.50.
Read the note: Twelve to Nothing · the FOMC tests scored; the curve went further
~ PartialThe 8 October buybackThe Door Was Rushed · 5 Oct$14.9bn vs $10bn and $20bn● Resolved
The 20 to 30 year operation, the sector the original $19.868bn was measured in and the one that drew $10.468bn on 24 September. Offers above $20bn confirm the queue is back across the long end; offers near ten say 1 October was a single-sector event; between the two, as the 6 October Premium pre-registered, the claim stands at the sector level only and is scored partial. It drew $14.886bn against a $6bn maximum, the full $6bn taken in ten of 34 issues (FiscalData, 8 October 2026): between the two reads, so partial, as written. The long-end-wide version waits for the next 10 to 20 year operation.
Read the note: The Door Was Rushed · three published levels answered; the queue returns
◆ NewThe regime's retirement testThe Price of Duration · 6 Oct5.60○ Open
A thirty-year close below 5.30 on a session carrying a downside labour or inflation surprise, with the ACM ten-year term premium back under 0.90, retires the name the note gives the regime; the floor thesis stands or falls on 4.85 separately. Registered with the term premium at 1.02; not approached in the first week, with the estimate at 1.08 on 2 October, the latest available.
Read the note: The Price of Duration · the regime named, the range redrawn, the reweight on the fired tell
~ PartialThe minutes expectationThe Price of Duration · 6 Octtwo halves → one held● Resolved
Stated in the note so that it could be wrong: the September minutes would read hawkish on inflation and silent on the long end. Hawkish held, all participants supporting September's rise and most seeing another by year end; silent did not. A few participants discussed the rise in longer-term yields and attributed it to a stronger economy, expected AI-related borrowing and geopolitical developments, and many judged financial conditions still supportive despite it (Federal Reserve, FOMC minutes, 7 October 2026). The staff decomposition, real rates and market commentary on the buyback programme and AI issuance, matches the desk's; the participants' explanation does not. Half of a compound claim held, so it is scored Partial, the same rule as the 11 September migration row.
Read the note: The Price of Duration · the regime named, the range redrawn, the reweight on the fired tell
FX8 scored · 4 held · 4 partial · 100% held or better
~ PartialDXYSix Pillars · 1 Jun99.2 → 102.2○ Open
The dollar trades a firm 98 to 100 range, held up by rate differentials and a constrained Fed. Firm was right and the range was low: it held the band through August, then broke above it to 102.2 at the 9 October close as the Fed delivered and the front end went to 4.92.
Read the note: Six Pillars · the structural-regime read
~ PartialDXYThe Floor Held. Again. · 10 Jun99.9 → 102.2○ Open
The dollar holds its range: no dovish softening, because the market never repriced the Fed lower. It eased to the range floor in August, then went through the top of it in September on the rise. No softening; the range broke upward.
Read the note: The Floor Held. Again. · the post-CPI rate-floor verdict
✓ HeldDXYThe Buyers Go Home. · 16 Jun99.5 → 102.2○ Open
The dollar holds firm: the relative winner in a world where every major central bank is boxed in. It softened toward the range floor in August, then went to 102.2 by the 9 October close as the Fed moved first and hardest.
Read the note: The Buyers Go Home. · the vanishing-bid thesis
✓ HeldDXYHeld Out for the IPOs · 9 Jun99.9 → 102.2○ Open
The dollar firms at the margin on US tech-export risk as the AI-capex story wobbles. It firmed, handed the move back, then firmed decisively into the September rise.
Read the note: Held Out for the IPOs · the AI valuation and IPO read
~ PartialDXYThe Tide Line · 14 Sep99.5 → 102.2○ Open
Firm but unpaid for its front end, 98.5 to 100.5. Firm was right, and the front end got paid: 102.2 at the 9 October close, through the top of the band, as October's second rise priced near seventy per cent.
Read the note: The Tide Line · the reweight, scored on the print
✓ HeldUSD/JPYSix Pillars · 1 Jun159.7 → 158.3○ Open
USD/JPY drifts toward 160, the level where Japan has historically intervened: intervention risk builds. It traded around 160 all summer, closed back through the line on 28 August, then went 160.39 to 155.30 in two sessions in the first week of September as the speculative short was washed out, and the Bank of Japan raised to 1.25% on 18 September. 160 belonged to Tokyo, as the note said.
Read the note: Six Pillars · the structural-regime read
✓ HeldUSD/JPYThe Buyers Go Home. · 16 Jun160.5 → 158.3○ Open
USD/JPY drifts lower only gradually as the BoJ-driven carry unwind is a slow burn. Lower it is, though it came as a gap rather than a grind: 155.30 in the week of 1 September, 157.4 at the 28 September settle and 158.3 at the 9 October close, with the Bank of Japan at 1.25.
Read the note: The Buyers Go Home. · the vanishing-bid thesis
~ PartialUSD/JPYThe Tide Line · 14 Sep154.5 → 158.3○ Open
Grinds 152 to 157 as the valve closes. It ground higher through the band to 158.9 on 24 September as the front end repriced, and closed 28 September at 157.4, a fraction through the top, and 158.3 at the 9 October close. The valve closed as described, the Bank of Japan at 1.25; the band was a touch low.
Read the note: The Tide Line · the reweight, scored on the print
Credit7 scored · 2 rotated · 5 missed · 29% held or better
↻ Rotated ⇆Credit, the tellTwelve to Nothing · 29 Sep3.02 → 3.24 vs 3.10● Resolved
3.10 and widening is the single development that moves the desk to the growth path on its own. It printed 3.12 on 30 September and 3.24 on 1 October (the published high yield credit spread index): the map wording is met and twenty points move to the growth path in the 5 October Premium, the published trigger acted on, which is what rotated means on this page. The stricter holds wording, defined in the 5 October Brief as four consecutive settles, was not met and is recorded, unscored, in its own row; the print has since traded both sides of the line, 3.03 and 3.09 then 3.15.
Read the note: Twelve to Nothing · the FOMC tests scored; the curve went further
◆ NewCredit, the conversionThe Price of Duration · 6 Oct3.10 · 4.83 → 3.15 · 4.80○ Open
Path B becomes the base case on 3.50 held for four consecutive settles, or on a two-year close through 4.65 with the March fed funds contract pricing less than one further rise. The return toward fifteen, as the note's scenario map and checklist worded it, needs two consecutive settles back inside 3.10 with claims steady and the two-year holding 4.80: tested on 6 and 7 October at 3.03 and 3.09 with the two-year at 4.79 and 4.77, through the line, so not met; 3.15 on 8 October. Until 12 October this row carried the note's invalidation-box wording, without the two-year leg; that wording and the note's one-leg closing wording fired and are scored in the row below. Registered at 3.10 and 4.83 on the 2 October settles; the March contract settled 95.69 on 9 October, close to two rises.
Read the note: The Price of Duration · the regime named, the range redrawn, the reweight on the fired tell
✗ MissedCredit, the return condition, looser wordingsThe Price of Duration · 6 Oct3.10 → 3.03 · 3.09 → 3.15● Resolved
The note's invalidation box and credit instrument row, and this row until 12 October, worded the return toward fifteen as consecutive settles back inside 3.10 with claims steady, without the two-year leg the scenario map, checklist and credit section carried; its closing argument needed credit alone. Credit printed 3.03 on 6 October and 3.09 on 7 October with claims at 199,000 (the published high yield credit spread index; Department of Labor, 1 October 2026), so the one-leg wording fired on the 6 October settle and the two-leg wording on the 7 October settle; the desk published nothing on either and 8 October printed 3.15. Scored as a miss against the wordings, the desk's own drafting fault, with the growth weight held at thirty-five because the stricter wording did not fire and the looser ones reversed within a session. The three-leg wording governs from 12 October.
Read the note: The Price of Duration · the regime named, the range redrawn, the reweight on the fired tell
⊘ Trigger not metCredit, the holds wordingThe Door Was Rushed · 5 Oct3.12 → 3.10● Resolved
The 14 and 29 September wording, a break of 3.10 that holds, defined in advance as four consecutive settles above the line. Two were in, 3.12 and 3.24; Friday 2 October printed 3.10, at the line, so the stricter wording was not met, as the 6 October Premium records. This is the condition for switching paths, not a forecast, and the desk had already rotated on the map wording, so it is shown here and not scored. The map wording, consecutive settles through the level, stands and is scored in the row above.
Read the note: The Door Was Rushed · three published levels answered; the queue returns · not scored
✗ MissedHY OASSix Pillars · 1 Jun~270 → 315bp○ Open
High-yield spreads stay contained at 250 to 290bp: no credit stress beneath the rate move. Contained for four months to a 2.60 low on 28 August, then 64bp wider in five weeks to 3.24 on 1 October, through the band and through the desk's 3.10 tell on two consecutive settles. Scored missed as the row said it would be; the desk's growth path is now live on its own published trigger.
Read the note: Six Pillars · the structural-regime read
✗ MissedHY OASThe Buyers Go Home. · 16 Jun2.71 → 3.15○ Open
High-yield spreads stay calm at 2.60 to 3.00%: the long-end pressure is supply, not fear. Calm through the summer; 3.24 on 1 October is through the ceiling and through the 3.10 tell. The supply reading of the long end still holds on the breakeven evidence; the calm did not.
Read the note: The Buyers Go Home. · the vanishing-bid thesis
✗ MissedHY OASHeld Out for the IPOs · 9 Jun2.78 → 3.15○ Open
High-yield spreads hold 2.70 to 3.00% through the AI-equity selloff: a discipline trade, not a credit event. The band held through the June selloff; it broke in late September on rates and went through the tell on 1 October with the Nasdaq at a record. Missed on the level.
Read the note: Held Out for the IPOs · the AI valuation and IPO read
✗ MissedHY OASThe Floor Held. Again. · 10 Jun2.78 → 3.15○ Open
High-yield spreads stay pinned 2.70 to 3.00%: the cross-check that the equity pressure is sector-local. It was, until it was not: 3.24 on 1 October with equities at highs is the credit channel opening on its own, which is the growth path's trigger, not the equity one.
Read the note: The Floor Held. Again. · the post-CPI rate-floor verdict
↻ Rotated ⇆HY OASThe Tide Line · 14 Sep2.70 → 3.15● Resolved
Drifts, 2.60 to 2.90. It drifted to 2.68 on 22 September, then 56bp in seven sessions to 3.24 on 1 October, through the condition the note published for the growth path and through the tell the same note named in its scenario map. The base case failed on this leg and the note's own Path B trigger fired, which is what the map was for. Scored Rotated: the stated trigger fired and the mapped growth path took the weight, the same treatment as the 29 September tell row.
Read the note: The Tide Line · the reweight, scored on the print
Commodities14 scored · 9 held · 2 partial · 1 rotated · 2 missed · 86% held or better
~ PartialBrentSix Pillars · 1 Jun→ ~105 (tape)○ Open
Brent trades a 90 to 100 range while the Iran war premium persists. It fell out of the range on the ceasefire, returned as it lapsed, ran to 106 on the Saudi pipeline shutdown, dipped under 96 as the pipeline restarted and closed 9 October near 105 on the tape, products leading on reports of US strike preparations. Through the top of the band by about five dollars, in the spirit of the call.
Read the note: Six Pillars · the structural-regime read
↻ RotatedBrentThe Buyers Go Home. · 16 Jun85 → 78 → ~105 (tape)● Resolved
Brent eases on the ceasefire while the long-end floor stays: energy relief lands in oil, not in duration. The relief held until the ceasefire expired and Brent recovered.
Read the note: The Buyers Go Home. · the vanishing-bid thesis
✓ HeldBrentThe Floor Held. Again. · 10 Jun→ ~105 (tape)○ Open
Brent stays rangebound but elevated on the unresolved Iran conflict. Elevated still: 106 at the September peak, near 105 at the 9 October close with the strait contested again.
Read the note: The Floor Held. Again. · the post-CPI rate-floor verdict
✓ HeldBrentThe Shock Writes. The Committee Waits. · 1 Sep90.5 → 98.4○ Open
The strait as a ratchet, not a panic; the pain trade is de-escalation; the 98th-percentile crude long is right until it is not. Brent went 90.49 to 106 without a gap day, the long grew and was right, then Saudi Arabia restored the East-West pipeline and the pain trade arrived: 98.4, and the long is the one paying.
Read the note: The Shock Writes. The Committee Waits. · the strait as a ratchet, not a panic
✓ HeldBrentThe Tide Line · 14 Sep104.6 → ~105 (tape)○ Open
100 to 110, products lead, the crack wide. Held the band for two weeks to 106, slipped under it as the pipeline restarted, and closed 9 October inside it at about 105 on the tape, the December contract at 104.72. Inside the band on the as-of date; the disarm legs the note registered, Brent under 95 with the margin through 55, a pipeline restart and a lane accord, stand at one delivered and three not.
Read the note: The Tide Line · the reweight, scored on the print
⇆ Branch resolved ⇆GoldTen Dollars Offered. One Accepted. · 20 Aug4523 → 4195 · 2Y +61bp vs 30Y +37bp● Resolved
Registered both branches in advance: sustained trade above 4,449 alongside enlarged buybacks is the fiscal read compounding; a return below it while the two-year leads yields higher is the one combination that would argue the dollar's hawkish case is real. Gold ran to 4,680 on 24 August, closed back under the line on 1 September and has closed below it on every session since 4 September, 4,195 at the 9 October close, while the two-year rose 61bp from the 20 August settle against 37bp on the thirty-year. The dollar branch fired, and what it argued for arrived: a unanimous rise on 16 September. Branch resolved, the dollar case, as the 13 October Brief scores it.
Read the note: Ten Dollars Offered. One Accepted. · the issuer's bid as signal, not flow · scored in Gold Lost the Line. The Dollar Kept the Case.
✗ MissedGoldSix Pillars · 1 Jun4485 → 4195○ Open
Gold consolidates in a 4,400 to 4,600 range. It drifted below the band on rising real yields, recovered into it, ran to 4,680 in late August, then fell through the floor of the band as the real ten-year went from 2.55 to 2.90: 4,195 on 9 October, 4.7% under the band.
Read the note: Six Pillars · the structural-regime read
✓ HeldGoldHeld Out for the IPOs · 9 Jun4222 → 4195○ Open
Gold trades neutral: no clear push from the AI-equity story either way. Rangey since, a record in August and within one per cent of the publish level at the 9 October close, on rates rather than on equities.
Read the note: Held Out for the IPOs · the AI valuation and IPO read
✓ HeldGoldThe Floor Held. Again. · 10 Jun4047 → 4195○ Open
Gold consolidates after its post-print unwind, then firms from 4,047 as the fiscal hedge reasserts. It firmed to 4,680 and has given nearly all of it back to real yields; about 150 dollars above the base at the 9 October close.
Read the note: The Floor Held. Again. · the post-CPI rate-floor verdict
~ PartialGoldThe Buyers Go Home. · 16 Jun4331 → 4195○ Open
Gold consolidates at elevated levels as the fiscal-and-bid hedge, not the war hedge. It held and pushed to records into August, then fell 12% from the peak as real yields rose 35bp in three weeks. Elevated by any longer measure, and 3% under the publish level.
Read the note: The Buyers Go Home. · the vanishing-bid thesis
✗ MissedGoldThe War Is Over. The Floor Isn't. · 19 Jun4188 → 4195○ Open
Gold lower on the dollar bid: with the war premium gone, gold trades the dollar. It went the other way first, to a 4,680 record in August while the dollar softened, and this page scored it missed at the 28 August mark; it came back through the publish level in September as the dollar went to 101 and was scored held at the 2 October mark. At the 9 October close it sits seven dollars above the publish level with the dollar at 102.2, a fraction offside, and the symmetric rule scores it as it finds it: missed, with the path stated in full.
Read the note: The War Is Over. The Floor Isn't. · the post-ceasefire floor, and gold on the dollar
✓ HeldGoldThe Tide Line · 14 Sep4348 → 4195○ Open
Consolidates under 4,449 with the two-year leading. Under it throughout, 4,195 at the 9 October close, and the two-year led every session that mattered.
Read the note: The Tide Line · the reweight, scored on the print
✓ HeldGoldThe High-Water Mark · 18 Augnet long 243k → 210k○ Open
The inflation hedge is crowding: a hedge the crowd already owns pays worse on the event. Speculative net length kept building to 243,334 contracts on 25 August and has since unwound to 210,335 on 6 October, the lowest of the eight weekly reports since 18 August, while the price fell about seven per cent from the 20 August settle. The crowd owned it, and it paid worse. Scored Held in the 13 October Brief.
Read the note: The High-Water Mark · the positioning read · scored in Gold Lost the Line. The Dollar Kept the Case.
✓ Held ⇆Gold, the controlThe Price of Duration · 6 Oct4141 → 4195 vs 4449○ Open
Registered gold as the control: gold under 4,449 confirms the reading; gold retaking 4,449 with breakevens rising would say the market had started reading credibility, and the desk would reverse on it. Gold went from 4,141 on 5 October to 4,195 at the 9 October close, still more than 250 dollars under the line, with the ten-year breakeven at 2.33 from 2.36. Neither leg of the reversal is close. Scored Held in the 13 October Brief.
Read the note: The Price of Duration · the regime named, the range redrawn · scored in Gold Lost the Line. The Dollar Kept the Case.
Equities6 scored · 3 held · 1 missed · 2 early · 50% held or better
✗ MissedSemis (SMH)Six Pillars · 1 Jun608 → 603○ Open
Semiconductors keep leading the tape higher on the AI-infrastructure build. They rolled over in June, fell to 542 in early September, led again into early October, then fell 4.3% in the week to 9 October to 603, under the publish level, while the S&P sat 2.8% above its own. Scored on the current tape, as the symmetric rule requires: not leading at the 9 October mark; it was held at the 2 October one.
Read the note: Six Pillars · the structural-regime read
✓ HeldS&P 500Six Pillars · 1 Jun7600 → 7812○ Open
The S&P 500 grinds higher on ample liquidity. Higher: 2.8% above the publish level at the 9 October close, with a record close on 6 October, the ten-year at 5.24 overhead and credit a few basis points through the desk's tell.
Read the note: Six Pillars · the structural-regime read
◐ EarlyNasdaqHeld Out for the IPOs · 9 Jun25930 → 27366○ Open
The Nasdaq goes range-bound to 5 to 10% lower as the AI valuation premium reprices. The thesis-direction drop came early (about 7% into the 10 June low) then reversed: open, currently offside by 5.5%, with the stated invalidation (HY OAS through 3.50) not fired at 3.15.
Read the note: Held Out for the IPOs · the AI valuation and IPO read
◐ EarlyNasdaq / AIThe Floor Held. Again. · 10 Jun25170 → 27366○ Open
The AI complex stays a range-bound, relative laggard. A forward-guidance call on the AI valuation reset: the tape has run against it since, open and currently offside by 8.7%, pending the stated invalidation.
Read the note: The Floor Held. Again. · the post-CPI rate-floor verdict
✓ HeldSemis (SMH)Held Out for the IPOs · 9 Jun591 → 603○ Open
Semiconductors underperform quality mega-caps as capex discipline bites. They did into September, outran the index into early October, then gave it back: since 9 June SMH is up 2.1% against 5.7% for the S&P at the 9 October close. Scored held on the current tape, as the symmetric rule requires; it was missed at the 2 October mark.
Read the note: Held Out for the IPOs · the AI valuation and IPO read
✓ HeldS&P 500The Tide Line · 14 Sep7657 → 7812○ Open
Range-bound, rates a ceiling; energy over the consumer complex. 7,552 to 7,819 over four weeks, 2.0% above where it started at the 9 October close, with the record close of 6 October made in the week the long end set its high.
Read the note: The Tide Line · the reweight, scored on the print
Process log
We log our own lateness here
Separately from market calls, so you can see both. These rows measure timeliness, not a view on the market, and they are not in the call count. On time: 1 of the desk's last 5 scoring notes.
✗ LateThe deliveryThe Tide Line · 14 Sepowed 17 Sep → scored 28 Sep● Resolved
The desk pre-committed in print to score the four tests above on the 17 September settle. They were scored on 28 September, seven sessions late, the second consecutive late delivery on a dated pre-commitment and the first to go unacknowledged at the time. Logged at the weight of a missed level. The fix is structural and in the 29 September note: publish what has settled, register what has not.
Read the note: The Tide Line · the reweight, scored on the print
✗ LateThe delivery, 2 OctoberTwelve to Nothing · 29 Sepowed 2 Oct → scored 5 Oct● Resolved
The payroll test was owed on the 2 October settle under the note's own structural rule, publish what has settled. The scoring Brief went out on Monday 5 October, one session later, the third note in a row to arrive after the settle it scores. Logged at the weight of a missed level, after the hits, as the 5 October Brief logs it.
Read the note: Twelve to Nothing · the FOMC tests scored; the curve went further
✗ LateThe delivery, 8 OctoberDuration Cleared. The Crowd Did Not. · 12 Octowed 9 Oct → published 12 Oct● Resolved
Registered 6 October, owed on the 8 October settle. Under the standard set on 29 September, publish what has settled, the scoring note was due on Friday 9 October; it was scheduled and not produced, and went out on Monday 12 October, one full session late. The fourth of the desk's last five notes to arrive after the settle it was owed on. Logged at full weight.
Read the note: Duration Cleared. The Crowd Did Not. · the retest, scored
Methodologydefinitions, sources and rules
Verdicts
- ✓ Held: the claim is true at the mark.
- ⇆ Branch resolved: a two-branch call where the tape picked a branch the note set out in advance. Counted as held.
- ~ Partial: half of a compound claim held, or the move the call named was delivered and then materially given back. Counted inside held or better and shown separately.
- ↻ Rotated: the note's stated invalidation or trigger fired and a mapped scenario from the same note took over. Counted inside held or better.
- Ran, then closed: a closed call that made at least 100 pips, 15 basis points or 1% before its invalidation fired. None at this mark.
- ◐ Early and ? Ambiguous: in the denominator, not in the numerator.
- ✗ Missed: the claim is false at the mark and was not delivered on the way to it.
- ⊘ Trigger not met: a condition for switching paths that did not fire. A condition is not a forecast, so it is shown and not scored.
- ◆ New: registered, not yet scored.
The headline
Held or better = (held + partial + rotated) ÷ every scored call, misses, early and ambiguous rows included in the denominator. At this mark: (47 + 11 + 3) ÷ 80 = 76.3%. Held alone: 47 ÷ 80 = 58.8%. Missed: 16 ÷ 80 = 20.0%.
Status and horizons
○ Open: the scenario is still in play and the as-of mark is a waypoint. ● Resolved: a stated trigger fired or the stated horizon passed, and the row is frozen. A call is marked while its thesis remains valid, unless its stated invalidation fires or a later note explicitly closes it. Where a note gave a tactical horizon, the row shows it, and where later notes carried that read into the regime call, the row says which notes and what the mark was at the end of the original horizon. The same rule applies to every FX call on this page.
Levels
US Treasury yields: the Treasury's daily par yield curve. FX, commodities and equities: end-of-day closes on the desk's feed; Brent is a continuous tape series rather than a named contract, which is why its rows say tape. Entry is the published level for each call; where a note's wording was to sell rallies or buy dips rather than enter at the market, the record checks that price traded through the entry after publication and before any invalidation. Every open row is marked to 9 October 2026. High-yield credit's official print lags a session, so the credit rows carry the 8 October print of 3.15.
Free from the desk
Get the next call before the data.
Every Brief and Analysis as a teaser, dated before the print and scored here afterwards. Premium unlocks the full scenario maps, levels and invalidation criteria.
This page is editorial commentary on observable market developments and a record of published views. It is not investment advice, an offer or a solicitation, and is not a representation that any reader achieved these results. Past performance is not indicative of future results. We read the data. We call the paths.