FO Research
The Record
Every Financial Oracle call, dated before the data and scored against the tape. 92 calls, 73% held or better, every miss shown.
The Record, scored to 16 November 2026, revised 17 November 2026
Dated before the data. Scored after it.
92 calls. 73% held or better. Every miss is on this page, and every number links to the note that made it.
Held includes 3 two-branch calls scored Branch resolved. Partials count inside held or better and are shown separately; held alone is 52/92 (56.5%). Also on the record: 1 early, 1 ambiguous, 2 new and not yet scored, 3 trigger not met (shown, not scored). Late deliveries sit in the process log, not in the call count.
The spine on the chart
Now and peak are both shown, measured from the published entry. These are research-call marks, not trading results; entries and exits are the reader's own.
The spine: our highest-conviction macro calls
Long dollar. No cuts. The floor holds.
One line per call; open any line for the reasoning and the path. Each is held from its entry to the 16 November close and marked while its thesis stands; none has hit its stated invalidation. These are marks on open calls, kept outside the scored count below.
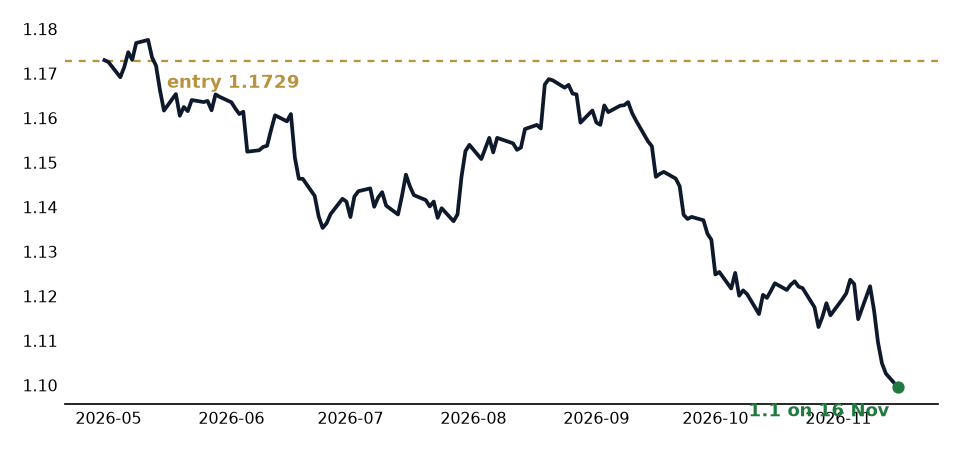
Short EUR/USD30 Apr1.1729 to 1.0996+733 pips (peak +733 pips)Held, open
The founding dollar-regime call: sell EUR rallies while US rate differentials and a constrained Fed keep the dollar bid. It gave most of the June move back through August, recovered it in September as the Fed moved first, and set a new peak on 7 October at 1.1196 as the long bond closed at its highest since 2002, with speculators carrying a record gross euro short into the move. Marked to 16 November at 1.0996, a new low for the move and a new peak for the call.
Read the note: Stronger for Longer; the dollar-regime call
Short GBP/USD30 Apr1.3605 to 1.3184+421 pips (peak +441 pips)Held, open
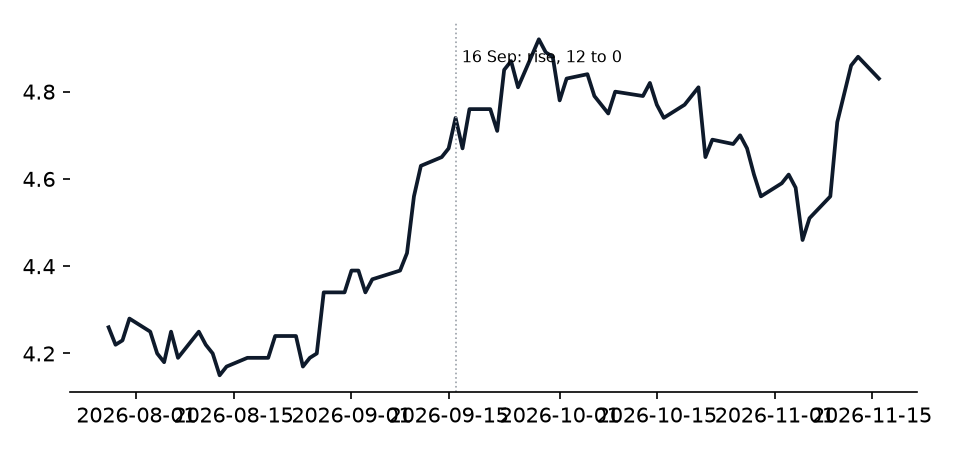
GBP upside capped while the dollar stays bid and the Bank of England lags the Fed. The Bank held 6 to 3 on 17 September while the Fed rose 12 to 0: the lag the note described, on the record. Marked to 16 November at 1.3184, after a rally to 1.3477 on 5 November was given back.
Read the note: Stronger for Longer; the dollar-regime call
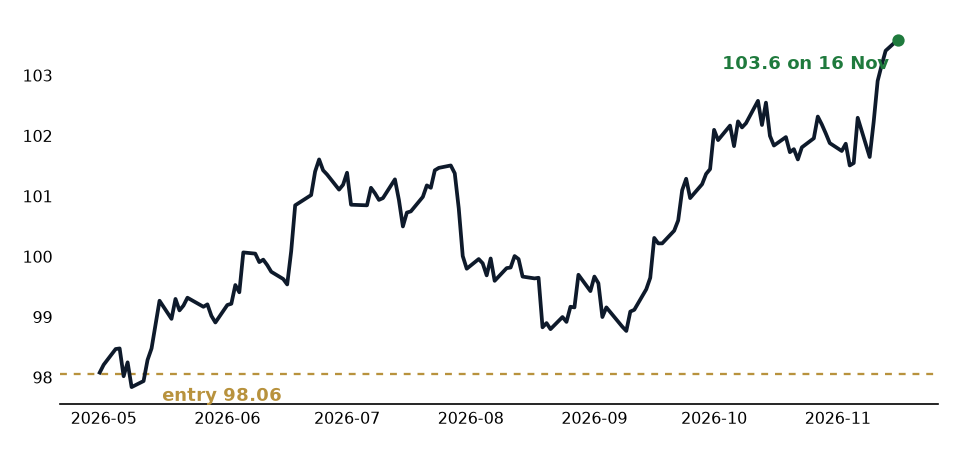
Long the dollar (DXY)30 Apr98.06 to 103.59+5.6% (peak +5.6%)Held, open
The dollar broadly higher for longer on rate differentials and US relative strength. A new peak on 7 October at 102.25, through the June high, as the long bond closed at its highest since 2002. Marked to 16 November at 103.59, a new high for the move, through 103 on three closes from 12 November.
Read the note: Stronger for Longer; the dollar-regime call
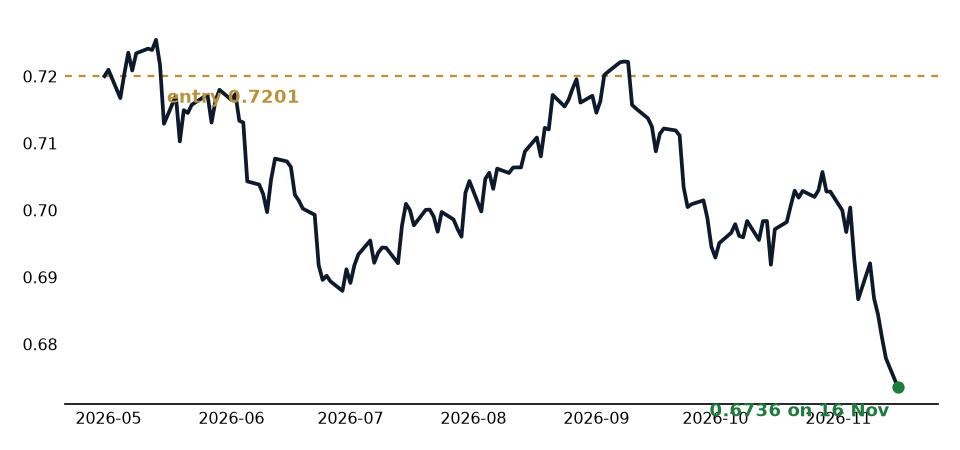
Short AUD/USD30 Apr0.7201 to 0.6736+465 pips (peak +465 pips)Held, open
Fade AUD rallies into broad dollar strength while China momentum stays soft. Marked to 16 November at 0.6736, a new peak for the call after a rally to 0.7058 on 29 October was given back.
Read the note: Stronger for Longer; the dollar-regime call
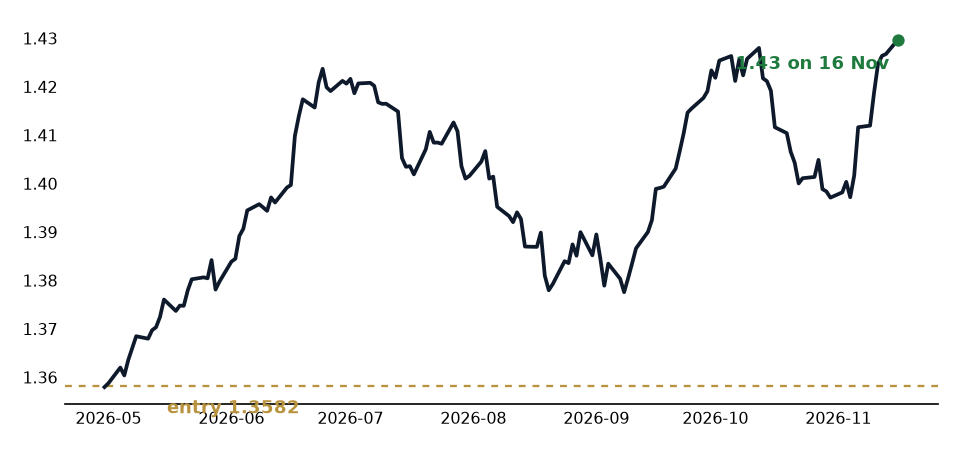
Long USD/CAD30 Apr1.3582 to 1.4297+715 pips (peak +715 pips)Held, open
USD/CAD higher on the oil and yield-spread divergence and a price-defence regime. A new peak on 5 October at 1.4260; four pips under it at the as-of date. Marked to 16 November at 1.4297, a new peak for the call; the pair eased to 1.3970 on 2 November and rebuilt from there.
Read the note: Stronger for Longer; the dollar-regime call
Short NZD/USD28 Apr0.5886 to 0.5496+390 pips (peak +390 pips)Held, open
NZD bearish while USD momentum and risk-off flows persist. The note was published as a 1 to 2 week tactical read, and at the end of that window (12 May) the pair was 79 pips above entry. The same bias was carried into the dollar regime by later notes: Stronger for Longer (30 April) on AUD and NZD, the 19 June Brief (short NZD up 52) and the 6 October Premium (AUD and NZD lower with the euro). Marked while that thesis stands, as every spine call is: 0.5612 at the 9 October close, a new peak on 7 October. Marked to 16 November at 0.5496, a new peak for the call.
Read the note: Dollar, Oil, Higher for Longer; the dollar, oil and rates regime call
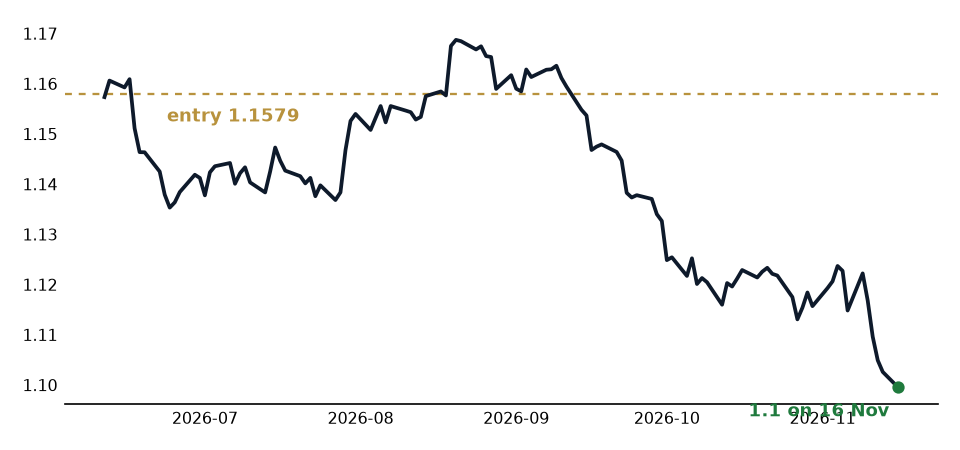
Short EUR/USD11 Jun1.1579 to 1.0996+583 pips (peak +583 pips)Held, open
EUR sold even on the ECB hike: tightening into a downgraded growth outlook is not a strong-currency story. The note set no horizon or invalidation of its own and framed the read inside the 30 April regime call, whose invalidation (a decisive Fed pivot to easing) has not fired; no later note closed it. The ECB rose again on 10 September and the euro fell anyway; a new peak on 7 October. Marked to 16 November at 1.0996, a new peak for the call.
Read the note: Both Sides. One Tell.; PPI and ECB, the dollar winner
Short GBP/USD15 Jun1.3450 to 1.3184+266 pips (peak +286 pips)Held, open
GBP soft into Warsh's hawkish hold and a firmer dollar. The note set no horizon or invalidation of its own and named the regime as stronger for longer; the 19 June Brief scored its base case as printed, and the 12 October Brief still marks the regime held with sterling at 1.3234. Offside through August; back onside when the hold became a rise. Marked to 16 November at 1.3184.
Read the note: New Chair. Same Floor.; the Warsh FOMC preview
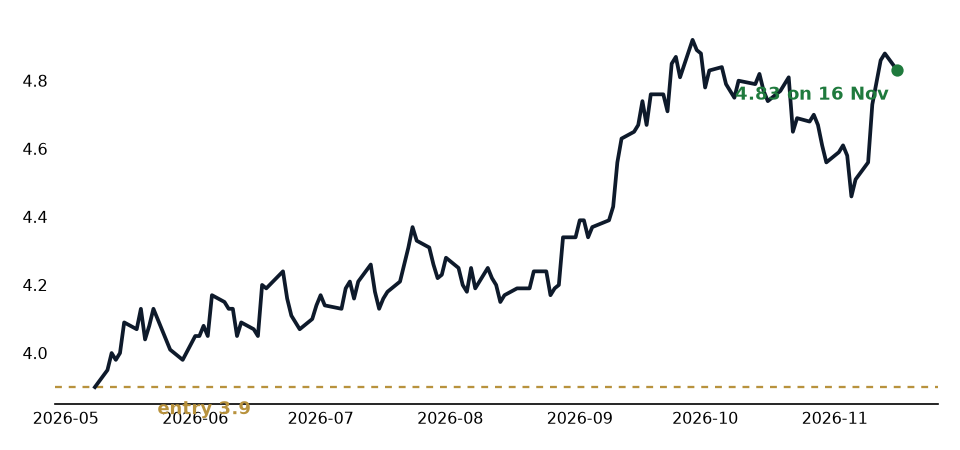
No cuts (US 2-year)8 May3.90% to 4.83%+93bp (peak +102bp)Held, open
The Fed cannot ease into a 4-handle inflation backdrop: the front end stays anchored and cut bets get priced out. They were, and then some: the committee raised the range to 3.75 to 4.00 on 16 September, 12 to 0, and the two-year held 4.80 through a payroll print of 29,000 on 2 October even as the strip took the October rise down to one chance in five, then closed 4.80 again on 9 October after dipping to 4.75 into the minutes. Marked to 16 November at 4.83%: through 4.65 to 4.46 on 5 November, never back to the high-3s, and back to 4.83 as a December rise was priced.
Read the note: The Long Bond Disconnect; term premium owns the long end
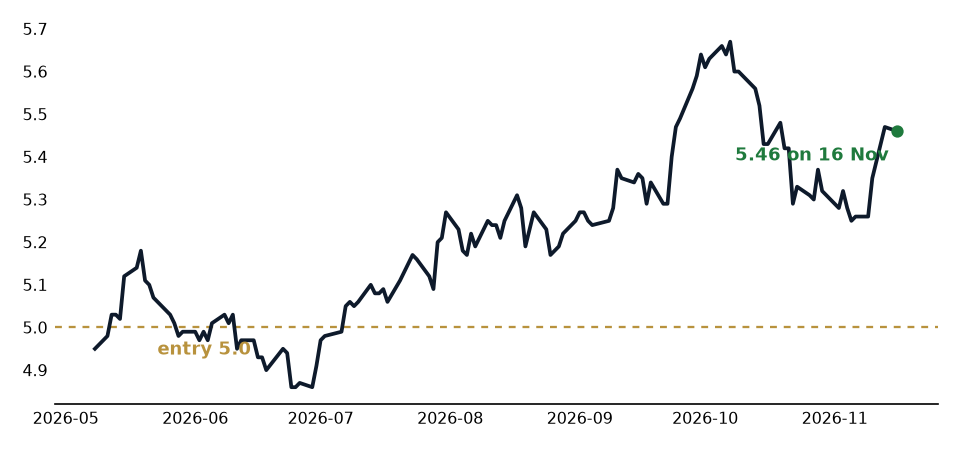
The 30-year floor holds8 May to 16 Jun~5.00% to 5.46%+46bp (peak +67bp)Held, open
Term premium and the deficit hold the long-end floor through every test: a hot jobs print, a soft CPI, a new chair, a ceasefire and its expiry, an enlarged issuer bid, a unanimous rise, a payroll print of 29,000 that could not move it and a $22bn thirty-year reopening that cleared at 5.618 with the long end closing lower on the day. It ran to 5.31 on 17 August, eased when the Treasury doubled its buybacks, went to 5.67 on 7 October, the highest close since July 2002, and closed 5.60 on 9 October with the breakeven at 2.33: the entire move and more was real yield. Marked to 16 November at 5.46%, after 5.25 on 5 November.
Read the note: The Floor / Floor Held / Buyers; the rate-floor thesis
* FX total: seven calls marked from entry to the 16 November close (Short EUR/USD 30 Apr +733, Short GBP/USD 30 Apr +421, Short AUD/USD 30 Apr +465, Long USD/CAD 30 Apr +715, Short NZD/USD 28 Apr +390, Short EUR/USD 11 Jun +583, Short GBP/USD 15 Jun +266); the peak total is +3,613. Entries are the published levels; each traded after publication. USD/JPY rows are level calls with no pip scoring. A research measure, not a trading result.
The full record: every stated cross-asset bias
The complete scorecard, grouped by theme
One line per call. Open a theme to see its rows; open a row for the note's own wording and the path. Unless flagged tactical, calls carry a multi-quarter horizon and stay open until their stated invalidation fires or their horizon passes.
Rates34 scored: 24 held, 1 partial, 9 missed; 74% held or better
The 30-year floor and its ranges21 scored: 17 held, 4 missed; 81% held or better
HeldUS 30-yearSix Pillars, 1 Jun~5.00 to 5.46Open
The 30-year stays pinned near 5.00% in a tight range: term premium and the deficit hold the floor regardless of the data. The floor held and the range did not: 5.31 in August, eased on the 19 August buyback expansion, then 5.67 on 7 October, the highest close since 2002. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: Six Pillars; the structural-regime read
HeldUS 30-yearHeld Out for the IPOs, 9 Jun5.01 to 5.46Open
The 30-year holds 5.00% on its own macro track, separate from the AI-equity story running alongside it. It has, by 56 basis points, while the Nasdaq went nowhere. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: Held Out for the IPOs; the AI valuation and IPO read
HeldUS 30-yearThe Floor Held. Again., 10 Jun5.03 to 5.46Open
The 30-year holds its floor through the CPI print: the floor is structural, not data-driven. It ran through the 5.15 top of the stated band to 5.31 in August and 5.67 by 7 October, the highest close since 2002, through three more CPI prints and a rise. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: The Floor Held. Again.; the post-CPI rate-floor verdict
HeldUS 30-yearThe Buyers Go Home., 16 Jun4.93 to 5.46Open
The 30-year holds even as the war premium drains: the floor is the vanishing bid, not the conflict. The conflict came back, the bid did not, and the issuer's own enlarged operations have not held the line either: 5.60 at the 9 October close, after 5.67 on 7 October, with the Treasury filling its ceiling at one enlarged operation in four. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: The Buyers Go Home.; the vanishing-bid thesis
HeldUS 30-yearThe Bid Comes Home, 23 Jun4.94 to 5.46Open
As the foreign official bid fades, the marginal buyer of American duration turns domestic. The direction held and the buyer arrived closer to home than the note wrote: on 19 August the issuer itself doubled its long-end buybacks, and by 1 October was filling its ceiling at one enlarged operation in four while the long end went to 5.67 on 7 October regardless. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: The Bid Comes Home; the domestic bid returns to the long end
HeldUS 30-yearThe Pipeline Translated, 25 Jun4.86 to 5.46Open
Supply-side inflation is global, giving every hawkish committee the same cover and holding the long-end floor. Japanese ten-year yields reached 3.055% on 24 September, the highest since 1996; gilts and bunds at multi-year highs. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: The Pipeline Translated; supply-side inflation goes global
HeldUS 30-yearThe Crack Arrives. The Floor Holds., 2 Jul4.98 to 5.46Open
The energy shock reaches the consumer through refining, and the long end does not soften into it. August CPI printed +0.4 on gasoline and the long end went 21bp higher in the fortnight after. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: The Crack Arrives. The Floor Holds.; the refining channel opens
HeldUS 30-yearThe Synchronised Floor, 10 Jul5.06 to 5.46Open
The floor is a cross-central-bank regime, not a US story: Fed and ECB turn hawkish together and duration stays offered. In September the Fed rose 12 to 0, the ECB rose, the Bank of Japan went to 1.25 on 7 to 2 and the Bank of England held 6 to 3 with three votes for a rise. The synchronised floor became a synchronised repricing. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: The Synchronised Floor; Fed and ECB hawkish together
HeldUS 30-yearThe Rebuild Begins. The Floor Hardens., 10 Jul5.06 to 5.46Open
Term premium rebuilds rather than fades, hardening the floor from below. The ten-year breakeven fell from 2.38 to 2.34 across the rise while the real ten-year went from 2.55 to 2.90: the whole September move was term premium and real yield, not inflation compensation. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: The Rebuild Begins. The Floor Hardens.; the floor hardens on supply
HeldUS 30-yearThe Disinflation Arrives., 15 Jul5.08 to 5.46Open
A soft June CPI bends the floor without breaking it: a bull steepener, not a broad rally. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: The Disinflation Arrives.; soft CPI, unbroken floor
HeldUS 30-yearThe Crack Premium, 21 Jul5.13 to 5.46Open
Refining margins, not crude, carry the shock into headline inflation and keep the long end pinned high. The August print carried it as written, +0.4 with gasoline +3.9%. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: The Crack Premium; refining, not crude, is the channel
HeldUS 30-yearThe Shock Round-Trips., 27 Jul5.12 to 5.46Open
Crude round-trips in four sessions and the long end keeps its level: the fades do not undo the ratchet. Brent has since run to 106 and back to 98; the long end kept none of the fades. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: The Shock Round-Trips.; the round-trip experiment
HeldUS 30-yearThe Ratchet, 28 Jul5.09 to 5.60Resolved
Each supply shock leaves the stance tighter than it found it while the fades leave it alone, and the next move is a rise, not a cut. Delivered on 16 September, 12 to 0, the first rise since 2023. Resolved.
Read the note: The Ratchet; shocks ratchet the stance tighter
HeldUS 30-yearThe Fed Held. The Hawks Didn't., 30 Jul5.21 to 5.46Open
A hold with three dissents for a rise keeps the long end elevated. The dissents became the decision seven weeks later. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: The Fed Held. The Hawks Didn't.; the three-dissent hold
HeldUS 30-yearSeven Dissents. One Direction., 3 Aug5.23 to 5.46Open
Seven hikes voted across three committees, none for cuts, and the long end holds its new range. It ran to 5.31, eased below the publish level on the buyback doubling, then went to 5.56 as the votes became decisions: the Fed 12 to 0 for a rise, the Bank of Japan 7 to 2. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: Seven Dissents. One Direction.; seven hikes voted, none for cuts
MissedUS 30-yearThe High-Water Mark, 18 Aug5.28 to 5.46Open
The tightening migrated from the committee to the curve, and the published 4.85 to 5.20 band was retired for 5.05 to 5.45, with a pre-commitment that a close through the top would be scored as a range miss on the day it printed. Twenty-six consecutive closes settled inside it, 5.17 to 5.40. The twenty-seventh closed 5.47 on 24 September and 28 September closed 5.56, eleven basis points above the line. The mechanism is not what failed; the level did, and it is scored as the note said it would be. Marked to 16 November at 5.46; the band was retired in the note and the miss stands.
Read the note: The High-Water Mark; the band redrawn, the miss scored
HeldUS 30-yearTen Dollars Offered. One Accepted., 20 Aug5.23 to 5.46Open
The buyback doubling read as signal, not flow: the issuer smooths the ink it will not stop writing, and rallies under its bid are distortion, not discovery. No rally came. The issuer has taken its ceiling at each enlarged operation since 9 September and the long end went to 5.56 regardless. The note's separate queue claim is scored in the pre-registered tests below. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: Ten Dollars Offered. One Accepted.; the issuer's bid as signal, not flow
HeldUS 30-yearThree Hands. One Pen., 25 Aug5.17 to 5.46Open
The issuer test, standing from 18 and 20 August: long-end rallies on the issuer's own bid are distortion, not discovery, and the witnesses that testify unaided are the two-year and gold. Both witnesses spoke through September: the two-year led the committee into a rise and gold fell through 4,449 as it did. Marked to 16 November: the thirty-year fell to 5.25 on 5 November, eight basis points under the 5.30 floor of the 6 October range, and closed 5.46 on 16 November (Treasury par curve). Still above the level the note defended; the floor thesis's own 4.85 falsification is sixty-one basis points away.
Read the note: Three Hands. One Pen.; the issuer test and its witnesses
MissedUS 30-yearThe Tide Line, 14 Sep5.34 to 5.46Open
Base case: the upper half of 5.05 to 5.45, the pivot beneath, auctions absorbed after concessions. The upper half held for eight sessions, then the band broke at 5.47 on 24 September and 5.56 on the 28th, the range miss the note pre-committed to. The concessions came and the auctions were absorbed badly: the 20-year stopped at 5.42, the 5-year at 5.033 on a 2.21 cover, the weakest since 2025. Marked to 16 November at 5.46; the miss stands as scored.
Read the note: The Tide Line; the reweight, scored on the print
MissedUS 30-yearThe Tide Line, 14 Sep5.37 to 5.46Open
The scenario map said a close through 5.45 moves weight to Path C, the inflation path. It fired on 24 September with the breakeven falling, and the 6 October Premium overrode it, cutting Path C to 20 because the move was term premium rather than inflation. Scored against the desk's wording, not the tape: the trigger should have carried a breakeven condition. Marked to 16 November at 5.46; the miss stands as scored.
Read the note: The Tide Line; the reweight, scored on the print
MissedUS 30-yearThe Price of Duration, 6 Oct5.63 to 5.29 on 22 OctResolved
Operating range 5.30 to 5.80 with the retired 5.45 as the pivot; a close through either edge is a range miss scored the day it prints, and the floor thesis keeps its own 4.85 falsification. Registered at 5.63 on the 2 October settle. The first full week printed 5.66, 5.64, 5.67, 5.60 and 5.60 (Treasury par curve, 5 to 9 October 2026), inside the range in its upper half with a new high on Wednesday: held for the week, as the 12 October Brief scores it, and open. The range then broke: the thirty-year settled 5.29 on 22 October, one basis point through the 5.30 floor, and 5.28 on 2 November, a second breach logged as evidence. Scored missed at full weight in The Committee Held. The Long End Did Not. (30 October) and The Barrel Fell. The Core Did Not. (11 November), which retired the range for 5.10 to 5.50.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell
NewUS 30-yearThe Barrel Fell. The Core Did Not., 11 Nov5.35 to 5.46Open
The thirty-year range is redrawn at 5.10 to 5.50 with 5.30 as the pivot; a settle through either edge is a miss scored the day it prints, and the 4.85 floor falsification is unchanged. Registered at 5.35 on the 10 November settle; 5.46 on 16 November, inside the range and four basis points under the top. New: registered, not yet scored.
Read the note: The Barrel Fell. The Core Did Not.; the map redrawn to the December meetings
The 2-year and the no-cuts call5 scored: 2 held, 1 partial, 2 missed; 60% held or better
HeldUS 2-yearThe Floor Held. Again., 10 Jun4.13 to 4.83Open
The 2-year stays anchored with cut pricing capped: the Fed cannot ease into a 4%-handle inflation backdrop. It could not. The committee raised on 16 September, 12 to 0, and the two-year closed 4.80 on 9 October after 4.92 on 28 September. Marked to 16 November at 4.83: the committee held on 29 October 10 to 2 with two votes for a rise, and no cut is priced.
Read the note: The Floor Held. Again.; the post-CPI rate-floor verdict
HeldUS 2-yearThe Buyers Go Home., 16 Jun4.05 to 4.83Open
The 2-year holds with no cuts priced into Warsh's first meeting: the constrained stance carries to the new chair. It carried to his third meeting, which delivered a rise. Marked to 16 November at 4.83, no cuts priced.
Read the note: The Buyers Go Home.; the vanishing-bid thesis
MissedUS 2-yearSix Pillars, 1 Jun~4.0 to 4.83Open
The 2-year drifts in the high-3s as the market waits on a Fed on hold. It repriced to a 4-handle and then to 4.92 as a rise was delivered instead: the no-cuts umbrella was right, this level call was not, by nearly a point. Marked to 16 November at 4.83; the miss stands.
Read the note: Six Pillars; the structural-regime read
PartialUS 2-yearThe Tide Line, 14 Sep4.65 to 4.83Open
Holds 4.50 to 4.75 as the rise lands; the committee's tenor fully priced. It went through the top to 4.92 as a second rise for October priced near seventy per cent: the direction and the mechanism held, the band did not. Since 9 October it went through the bottom of the band too, 4.46 on 5 November, and closed 4.83 on 16 November. Partial stands: the mechanism held, the band did not.
Read the note: The Tide Line; the reweight, scored on the print
MissedUS 2-yearThe Price of Duration, 6 Oct4.83 to 4.61 on 29 OctResolved
The two-year holds 4.65 to 4.95 in the base case. It held through the CPI print on 14 October, scored held in The Print Was Hot. The Tape Sold It., then closed 4.61 on 29 October, the first close through the floor, and 4.46 on 5 November. Back inside at 4.83 on 16 November, which does not reverse the miss (Treasury par curve). Missed at full weight in The Barrel Fell. The Core Did Not.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell; scored in The Barrel Fell. The Core Did Not.
Curve and breakevens8 scored: 5 held, 3 missed; 63% held or better
Held2s30sThe Floor Held. Again., 10 Jun+90 to +63bpOpen
The 2s30s curve stays steep, a market pricing structural supply at the long end while the front waits on the Fed. It steepened to a 108bp extreme in August, bear-flattened to 53bp on 21 September as the front end led the committee into a rise, and re-steepened to 80 by 2 October as the strip took October down to one chance in five and the long end went further: the front end is waiting on the Fed again and the long end is pricing supply. Ten basis points flatter than at entry, on the mechanism the call described. Marked to 16 November at 63bp: still positively sloped and steep by the standard of the last three years, twenty-seven basis points flatter than at entry.
Read the note: The Floor Held. Again.; the post-CPI rate-floor verdict
Held2s30sThe Buyers Go Home., 16 Jun+88 to +63bpOpen
The 2s30s curve holds steep, the shape of a bid problem at the long end. The bid problem is now visible in the issuer's own operations, $46bn offered into a $6bn buyback on 1 October, and the curve re-steepened to 80 as the front end fell on a weak payroll and the long end did not. Marked to 16 November at 63bp, twenty-five basis points flatter than at entry and still steep.
Read the note: The Buyers Go Home.; the vanishing-bid thesis
Branch resolved two-branchSept hike pricingSeven Dissents. One Direction., 3 Aug66% to ~50% to deliveredResolved
The pre-registered test, quoted as published: hold above half through benign data and the ratchet is priced. It did not hold. Pricing settled below half at three consecutive post-CPI sessions and the desk wrote the reversal note it had pre-committed to: the reversal branch fired, and it was not the desk's base case. It then re-armed to near 90% on the August CPI and the rise was delivered on 16 September, 12 to 0. The direction the note argued arrived six weeks later; the test it registered failed on its own terms, and at the time the desk scored the row missed. Both branches were registered before the event, so under the rule dated 29 October 2026 the row is Branch resolved, the reversal branch.
Read the note: Seven Dissents. One Direction.; seven hikes voted, none for cuts
Held2s30sThe Tide Line, 14 Sep+69 to +63bpOpen
Flattens further, the migration's bear flattener. It did, 69 to 53bp on 21 September, then re-steepened to 80 by the 9 October close on term premium as the long end went further without the committee. Eleven basis points steeper than at entry; the flattener the note described has been a steepener since the 23rd. Re-scored on the current tape, as the symmetric rule requires: the curve flattened back to 57bp on 12 November and closed 63bp on 16 November, six basis points flatter than at entry. Held at this mark; it was partial at the 9 October one.
Read the note: The Tide Line; the reweight, scored on the print
Missed10-year breakevenThe Tide Line, 14 Sep2.36 to 2.20Open
2.30 to 2.45, the three-month high held. Inside the band throughout, 2.31 to 2.40, and falling into the rise: 2.38 on the eve of the decision, 2.34 on 28 September and 2.33 on 9 October. The credibility the committee bought is priced here, and it is why the desk reads the long-end move as term premium rather than a pass-through. The band then broke on the low side: 2.29 on 2 November, the first close under 2.30, then 2.24 on 5 November and 2.20 at the 16 November close (FRED). Missed, low side, scored the same way The Barrel Fell. The Core Did Not. scored the 6 October band.
Read the note: The Tide Line; the reweight, scored on the print
Missed10-year breakeven, the bandThe Price of Duration, 6 Oct2.33 to 2.24 on 5 NovResolved
The base case carried a ten-year breakeven of 2.25 to 2.45. It closed 2.24 on 5 November, 2.20 on 10 November and 2.20 on 16 November (FRED). Missed, low side: scored against the desk's own band even though the fall is the opposite of the risk the band was written for, as the 11 November Premium scored it.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell; scored in The Barrel Fell. The Core Did Not.
MissedTerm premiumThe Price of Duration, 6 Oct1.10 to 0.94 on 22 OctResolved
The term premium stays above one point in the base case. The New York Fed's ten-year estimate was 0.94 on 22 October, 0.91 on 30 October and 0.87 on 6 November, the latest estimate (FRED). Missed at full weight in The Barrel Fell. The Core Did Not.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell; scored in The Barrel Fell. The Core Did Not.
HeldDuration clears at a priceThe Price of Duration, 6 Oct10Y 5.300; 30Y 5.618Resolved
The price of duration is set at the auction and the buyback rather than at the meeting, and the long end finds buyers at a price rather than rallying on weak data. The ten-year reopening stopped at 5.300 and the thirty-year at 5.618, the highest of the cycle, with 72.3 per cent to indirect bidders and 6.8 to dealers (TreasuryDirect, 8 October 2026). Scored held in Duration Cleared. The Crowd Did Not.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell; scored in Duration Cleared. The Crowd Did Not.
Fed and pre-registered tests19 scored: 12 held, 3 partial, 3 missed, 1 ambiguous; 79% held or better
Branch resolved two-branchThe keynoteThree Hands. One Pen., 25 Aug~36% to ~50%Resolved
The desk expected continuity and registered the risk branch: conditions named insufficient, progress named stalled, the front end leading, September toward the coin flip. The risk branch fired nearly verbatim. It was not the desk's base case, and at the time the desk scored itself missed at full weight, the miss first, in The Chair Speaks. The Pen Stays. Both branches were registered before the event, so under the rule dated 29 October 2026 the row is Branch resolved, the risk branch.
Read the note: Three Hands. One Pen.; the issuer test and its witnesses
HeldThe benchmark revisionThree Hands. One Pen., 25 Aug-79kResolved
Registered: a revision under roughly 300,000 disarms the collision's second hand and leaves the keynote alone on the stage. It printed minus 79,000 against a consensus near plus 183,000, and the session traded entirely on the speech.
Read the note: Three Hands. One Pen.; the issuer test and its witnesses
HeldJuly core PCEThree Hands. One Pen., 25 Aug0.2 / 3.3Resolved
Registered: an in-line print changes nothing, because the desk's dated inflation test is the 11 September CPI. It printed 0.2 on the month and 3.3 on the year, in line. Nothing changed.
Read the note: Three Hands. One Pen.; the issuer test and its witnesses
HeldBank of KoreaThree Hands. One Pen., 25 Aug2.75 to 3.00Resolved
Registered: a second rise to 3.00% extends the synchronised floor by another jurisdiction. It printed 25 basis points to 3.00, back to back, one dissent, framed by the governor as pre-emptive.
Read the note: Three Hands. One Pen.; the issuer test and its witnesses
HeldThe printJuly Never Happened. September Re-Arms., 7 Sep70% to ~90%Resolved
Marked 60 / 20 / 20 on the labour leg and held the formal reweight for the print: a hot August CPI seals the rise, a cool one with the crack still wide earns nothing. It printed hot, +0.4 with gasoline +3.9%, and sealed it: near 70% on the eve, nearly 90% on the release tick, with the dollar flat and the long end down. The asymmetry printed as written.
Read the note: July Never Happened. September Re-Arms.; the labour leg re-arms the rise
PartialThe migrationThe Issuer Offered Six. The Market Sold It., 11 Sep2Y 4.63 to 4.92; 30Y 5.35 to 5.56Open
A two-year that keeps rising into the print while the long end stalls is the migration, and 5.45 holds. The two-year kept rising, 4.63 to 4.92; the long end did not stall, it went to 5.56 through the 5.45 the note called unbroken. Half the read held and the half that was a level did not.
Read the note: The Issuer Offered Six. The Market Sold It.; the migration into the print
HeldThe voteThe Tide Line, 14 Septo 12 to 0Resolved
A rise with two dissents or fewer confirms the committee has joined the curve. It printed 12 to 0, the first rise since 2023, to a 3.75 to 4.00 range.
Read the note: The Tide Line; the reweight, scored on the print
HeldThe statement and the dotsThe Tide Line, 14 Septo 4.1 / 4.1Resolved
One further rise beside the delivered one matches the strip, with the energy clause named as the thing to watch. The median carried exactly one, 4.1% for 2026 and 4.1% for 2027, a plateau not a cycle, and the energy language was deleted.
Read the note: The Tide Line; the reweight, scored on the print
AmbiguousThe curve by the Thursday settleThe Tide Line, 14 Sep69 to 62 to 80bpResolved
Registered as a rise that flattens, the two-year up more than the thirty-year or the long bond lower but inside 5.05. Ambiguous as published, and the desk does not resolve its own ambiguity in its own favour. On the owed settle the long bond was lower at 5.29 but nowhere near 5.05, and 2s30s widened a basis point, 61 to 62. Over the fuller window the flattening arrived, to 53bp on 21 September, then reversed to 80 by the 9 October close. The wording is the desk's fault.
Read the note: The Tide Line; the reweight, scored on the print
MissedThe chair on the pressureThe Tide Line, 14 Sep4.74 to 4.67 on the owed settleResolved
Registered verbatim: not the words, which the desk does not score, but whether the front end holds the rise through the press conference. The two-year went 4.67 to 4.74 on the decision and back to 4.67 at the 17 September settle. It gave back the day's rise exactly, on the settle the test was owed on. The front end has since gone to 4.92; the test was written to be scored on the owed settle and it is scored there.
Read the note: The Tide Line; the reweight, scored on the print
HeldThe buyback queueTen Dollars Offered. One Accepted., 20 Aug$19.9bn to $39.6bnOpen
Built on a single number, $19.868bn of offers against a $2bn door in the 20 to 30 year sector, and registered the test in dollars. Three operations near ten billion followed and the desk retired the claim on 29 September. On 1 October the 10 to 20 year operation drew $46.391bn against a $6bn maximum, 7.7 times the door, the full $6bn taken in two of 41 issues at 67.398 and 75.976. The August claim stands in its original form: the queue was waiting for the price. The retirement is scored as the desk's miss in the row below. The retest on 8 October in the measured sector drew $14.886bn against $6bn, between the two pre-registered reads: partial, scored in its own row. The ten to twenty year sector kept queueing: $40.836bn offered against $6bn on 15 October and $39.636bn on 4 November, the full maximum bought each time (FiscalData), as scored in the 30 October Brief and the 11 November Premium.
Read the note: Ten Dollars Offered. One Accepted.; the issuer's bid as signal, not flow
HeldThe 2 October payrollsTwelve to Nothing, 29 Sep4.78 to 4.83 vs 4.80Resolved
Registered before the print: a two-year that holds 4.80 through it says the second rise is real; through 4.65 says the strip got ahead. The print was 29,000; the two-year went in at 4.78, below the line, and settled 4.83, above it (Treasury, 1 and 2 October 2026). Held on the settle the test was written for, with the strip cutting October to one chance in five the same afternoon, which the scoring note says beside the result.
Read the note: Twelve to Nothing; the FOMC tests scored; the curve went further
MissedThe 1 October buybackTwelve to Nothing, 29 Sep$46.4bn vs the $20bn lineResolved
The first 10 to 20 year operation since the queue claim was retired: offers near $20bn would say the desk retired it too early. It drew $46.391bn against a $6bn door (TreasuryDirect, 1 October 2026). The retirement was the desk's miss, scored at full weight in the 5 October Brief; the August thesis is reinstated above.
Read the note: Twelve to Nothing; the FOMC tests scored; the curve went further
HeldBreakevens, the discriminatorTwelve to Nothing, 29 Sep2.34 to 2.20 vs 2.50Open
Inflation compensation falling while nominal yields rise reads as term premium and supply, not an expectations shock. Through May's 2.50 high, the story becomes a credibility problem and the map changes with it. 2.33 at the 9 October close, down three on the week while December Brent rose from 100.20 to 104.72 and the long end set a new high: supply, not pass-through, and moving away from 2.50. Scored: the breakeven peaked at 2.38 on 28 October and closed 2.20 on 16 November (FRED), never near 2.50 through Brent's run to 117. Supply, not pass-through. The same 2.50 line was restated in The Price of Duration on 6 October and scored held in The Committee Held. The Long End Did Not. and The Barrel Fell. The Core Did Not. The two registrations are scored as one row at this mark. Held.
Read the note: Twelve to Nothing; the FOMC tests scored; the curve went further
PartialThe 8 October buybackThe Door Was Rushed, 5 Oct$14.9bn vs $10bn and $20bnResolved
The 20 to 30 year operation, the sector the original $19.868bn was measured in and the one that drew $10.468bn on 24 September. Offers above $20bn confirm the queue is back across the long end; offers near ten say 1 October was a single-sector event; between the two, as the 6 October Premium pre-registered, the claim stands at the sector level only and is scored partial. It drew $14.886bn against a $6bn maximum, the full $6bn taken in ten of 34 issues (FiscalData, 8 October 2026): between the two reads, so partial, as written. The long-end-wide version waits for the next 10 to 20 year operation.
Read the note: The Door Was Rushed; three published levels answered; the queue returns
NewThe regime's retirement testThe Price of Duration, 6 Oct5.60 to 5.46Open
A thirty-year close below 5.30 on a session carrying a downside labour or inflation surprise, with the ACM ten-year term premium back under 0.90, retires the name the note gives the regime; the floor thesis stands or falls on 4.85 separately. Registered with the term premium at 1.02; not approached in the first week, with the estimate at 1.08 on 2 October, the latest available. Not met to 16 November: the thirty-year closed below 5.30 on several sessions from 22 October with the term premium estimate under 0.90 by 5 November, but on the refunding, an equity sell-off and a strong payrolls report rather than a downside surprise (The Barrel Fell. The Core Did Not., 11 November). Still registered, still open.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell
PartialThe minutes expectationThe Price of Duration, 6 Octtwo halves to one heldResolved
Stated in the note so that it could be wrong: the September minutes would read hawkish on inflation and silent on the long end. Hawkish held, all participants supporting September's rise and most seeing another by year end; silent did not. A few participants discussed the rise in longer-term yields and attributed it to a stronger economy, expected AI-related borrowing and geopolitical developments, and many judged financial conditions still supportive despite it (Federal Reserve, FOMC minutes, 7 October 2026). The staff decomposition, real rates and market commentary on the buyback programme and AI issuance, matches the desk's; the participants' explanation does not. Half of a compound claim held, so it is scored Partial, the same rule as the 11 September migration row.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell
MissedThe queue across the long endDuration Cleared. The Crowd Did Not., 12 Oct$14.9bn to $10.7bnResolved
The queue of sellers runs across the whole long end, not just one sector. On 27 October the twenty to thirty year operation drew $10.746bn against the $6bn maximum, the single-sector reading the desk registered (FiscalData). Missed on the desk's own wording, scored in The Committee Held. The Long End Did Not.
Read the note: Duration Cleared. The Crowd Did Not.; the retest, scored; scored in The Committee Held. The Long End Did Not.
HeldThe CPI testDuration Cleared. The Crowd Did Not., 12 Oct30Y 5.52; breakeven 2.35Resolved
Registered that the test was the breakeven's reaction, not the headline: a print that leaves the thirty-year near 5.60 and the breakeven near 2.33 is the regime again. The 14 October settle printed the breakeven at 2.35 and the thirty-year at 5.52 (FRED; Treasury par curve). Scored held in The Print Was Hot. The Tape Sold It.
Read the note: Duration Cleared. The Crowd Did Not.; the retest, scored; scored in The Print Was Hot. The Tape Sold It.
HeldThe 4.80 line through the CPITwelve to Nothing, 29 Sep4.80 vs 4.82Resolved
The 4.80 line, published as the test of whether the second rise is real, held through the September CPI print at 4.82 (Treasury par curve, 14 October 2026). Scored held in The Print Was Hot. The Tape Sold It.
Read the note: Twelve to Nothing; the FOMC tests scored; the curve went further; scored in The Print Was Hot. The Tape Sold It.
FX11 scored: 5 held, 5 partial, 1 early; 91% held or better
PartialDXYSix Pillars, 1 Jun99.2 to 103.59Open
The dollar trades a firm 98 to 100 range, held up by rate differentials and a constrained Fed. Firm was right and the range was low: it held the band through August, then broke above it to 102.2 at the 9 October close as the Fed delivered and the front end went to 4.92. Marked to 16 November at 103.59, further above the band: firm was right, the band was low. Partial stands.
Read the note: Six Pillars; the structural-regime read
PartialDXYThe Floor Held. Again., 10 Jun99.9 to 103.59Open
The dollar holds its range: no dovish softening, because the market never repriced the Fed lower. It eased to the range floor in August, then went through the top of it in September on the rise. No softening; the range broke upward. Marked to 16 November at 103.59, further above the band: firm was right, the band was low. Partial stands.
Read the note: The Floor Held. Again.; the post-CPI rate-floor verdict
HeldDXYThe Buyers Go Home., 16 Jun99.5 to 103.59Open
The dollar holds firm: the relative winner in a world where every major central bank is boxed in. It softened toward the range floor in August, then went to 102.2 by the 9 October close as the Fed moved first and hardest. Marked to 16 November at 103.59, a new high for the move.
Read the note: The Buyers Go Home.; the vanishing-bid thesis
HeldDXYHeld Out for the IPOs, 9 Jun99.9 to 103.59Open
The dollar firms at the margin on US tech-export risk as the AI-capex story wobbles. It firmed, handed the move back, then firmed decisively into the September rise. Marked to 16 November at 103.59.
Read the note: Held Out for the IPOs; the AI valuation and IPO read
PartialDXYThe Tide Line, 14 Sep99.5 to 103.59Open
Firm but unpaid for its front end, 98.5 to 100.5. Firm was right, and the front end got paid: 102.2 at the 9 October close, through the top of the band, as October's second rise priced near seventy per cent. Marked to 16 November at 103.59, further above the band: firm was right, the band was low. Partial stands.
Read the note: The Tide Line; the reweight, scored on the print
HeldUSD/JPYSix Pillars, 1 Jun159.7 to 159.42Open
USD/JPY drifts toward 160, the level where Japan has historically intervened: intervention risk builds. It traded around 160 all summer, closed back through the line on 28 August, then went 160.39 to 155.30 in two sessions in the first week of September as the speculative short was washed out, and the Bank of Japan raised to 1.25% on 18 September. 160 belonged to Tokyo, as the note said. Marked to 16 November at 159.42: back under 160 on every close since 9 October, high 159.88 on 13 November.
Read the note: Six Pillars; the structural-regime read
HeldUSD/JPYThe Buyers Go Home., 16 Jun160.5 to 159.42Open
USD/JPY drifts lower only gradually as the BoJ-driven carry unwind is a slow burn. Lower it is, though it came as a gap rather than a grind: 155.30 in the week of 1 September, 157.4 at the 28 September settle and 158.3 at the 9 October close, with the Bank of Japan at 1.25. Marked to 16 November at 159.42, still lower than the publish level, by about a yen.
Read the note: The Buyers Go Home.; the vanishing-bid thesis
PartialUSD/JPYThe Tide Line, 14 Sep154.5 to 159.42Open
Grinds 152 to 157 as the valve closes. It ground higher through the band to 158.9 on 24 September as the front end repriced, and closed 28 September at 157.4, a fraction through the top, and 158.3 at the 9 October close. The valve closed as described, the Bank of Japan at 1.25; the band was a touch low. Marked to 16 November at 159.42, further through the top of the band. Partial stands.
Read the note: The Tide Line; the reweight, scored on the print
PartialDXYThe Price of Duration, 6 Oct102.10 to 103.59Open
The dollar firm in a 100.5 to 103 band. Inside it from 6 October to 11 November, 101.51 to 102.91, and scored held in the 11 November Premium; then through the top, 103.17 on 12 November and 103.59 on 16 November. Firm was right and the band was low: partial, on the same reading as the earlier dollar range rows.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell
EarlyThe dollar, the tactical stanceThe Print Was Hot. The Tape Sold It., 15 Oct102.53 to 103.59 vs 103Resolved
The dollar's run is crowded and due a pullback: the tactical stance moves to reduce, with a dollar index close through 103 registered to score the stance early at full weight. The pullback came, to 101.51 on 4 November, and was given back: scored partial in the 30 October Brief and the 11 November Premium. The index then closed through 103 on 12, 13 and 16 November, at 103.17, 103.41 and 103.59 on the desk feed. The registered early-scoring line printed: scored early at full weight.
Read the note: The Print Was Hot. The Tape Sold It.; the tactical stance on the dollar
HeldEUR/USD, the positioning caveatThe Price of Duration, 6 Oct1.1113 low, 1.1157 settle (14 Oct)Resolved
Positions of the size the positioning report showed materially raise the risk of profit-taking and short-covering; a retracement needs no catalyst and is not a reversal. On CPI day the dollar index made an eighteen-month high at 102.95 and settled 102.53, and the euro printed 1.1113 and settled 1.1157: the failure at the high the caveat described. Scored held in Duration Cleared. The Crowd Did Not. and The Print Was Hot. The Tape Sold It.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell; scored in The Print Was Hot. The Tape Sold It.
Credit8 scored: 2 rotated, 6 missed; 25% held or better
Rotated two-branchCredit, the tellTwelve to Nothing, 29 Sep3.02 to 3.24 vs 3.10Resolved
3.10 and widening is the single development that moves the desk to the growth path on its own. It printed 3.12 on 30 September and 3.24 on 1 October (the published high yield credit spread index): the map wording is met and twenty points move to the growth path in the 5 October Premium, the published trigger acted on, which is what rotated means on this page. The stricter holds wording, defined in the 5 October Brief as four consecutive settles, was not met and is recorded, unscored, in its own row; the print has since traded both sides of the line, 3.03 and 3.09 then 3.15.
Read the note: Twelve to Nothing; the FOMC tests scored; the curve went further
Trigger not metCredit, the conversionThe Price of Duration, 6 Oct3.10; 4.83 to 3.48 peak; 4.46 lowResolved
Path B becomes the base case on 3.50 held for four consecutive settles, or on a two-year close through 4.65 with the March fed funds contract pricing less than one further rise. The return toward fifteen, as the note's scenario map and checklist worded it, needs two consecutive settles back inside 3.10 with claims steady and the two-year holding 4.80: tested on 6 and 7 October at 3.03 and 3.09 with the two-year at 4.79 and 4.77, through the line, so not met; 3.15 on 8 October. Until 12 October this row carried the note's invalidation-box wording, without the two-year leg; that wording and the note's one-leg closing wording fired and are scored in the row below. Registered at 3.10 and 4.83 on the 2 October settles; the March contract settled 95.69 on 9 October, close to two rises. Not met when the map was retired on 11 November: credit peaked at 3.48 on 5 November and never settled through 3.50; the two-year closed through 4.65 from 29 October but futures still priced a December rise in full, so the second half of that route did not print (The Barrel Fell. The Core Did Not.). A condition for switching paths, shown, not scored.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell; not scored
MissedCredit, the return condition, looser wordingsThe Price of Duration, 6 Oct3.10 to 3.03; 3.09 to 3.15Resolved
The note's invalidation box and credit instrument row, and this row until 12 October, worded the return toward fifteen as consecutive settles back inside 3.10 with claims steady, without the two-year leg the scenario map, checklist and credit section carried; its closing argument needed credit alone. Credit printed 3.03 on 6 October and 3.09 on 7 October with claims at 199,000 (the published high yield credit spread index; Department of Labor, 1 October 2026), so the one-leg wording fired on the 6 October settle and the two-leg wording on the 7 October settle; the desk published nothing on either and 8 October printed 3.15. Scored as a miss against the wordings, the desk's own drafting fault, with the growth weight held at thirty-five because the stricter wording did not fire and the looser ones reversed within a session. The three-leg wording governs from 12 October.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell
Trigger not metCredit, the holds wordingThe Door Was Rushed, 5 Oct3.12 to 3.10Resolved
The 14 and 29 September wording, a break of 3.10 that holds, defined in advance as four consecutive settles above the line. Two were in, 3.12 and 3.24; Friday 2 October printed 3.10, at the line, so the stricter wording was not met, as the 6 October Premium records. This is the condition for switching paths, not a forecast, and the desk had already rotated on the map wording, so it is shown here and not scored. The map wording, consecutive settles through the level, stands and is scored in the row above.
Read the note: The Door Was Rushed; three published levels answered; the queue returns; not scored
MissedHY OASSix Pillars, 1 Jun~270bp to 3.23Open
High-yield spreads stay contained at 250 to 290bp: no credit stress beneath the rate move. Contained for four months to a 2.60 low on 28 August, then 64bp wider in five weeks to 3.24 on 1 October, through the band and through the desk's 3.10 tell on two consecutive settles. Scored missed as the row said it would be; the desk's growth path is now live on its own published trigger. Since 9 October spreads went to 3.48 on 5 November and printed 3.23 on 13 November, the latest print (ICE BofA via FRED). The miss stands.
Read the note: Six Pillars; the structural-regime read
MissedHY OASThe Buyers Go Home., 16 Jun2.71 to 3.23Open
High-yield spreads stay calm at 2.60 to 3.00%: the long-end pressure is supply, not fear. Calm through the summer; 3.24 on 1 October is through the ceiling and through the 3.10 tell. The supply reading of the long end still holds on the breakeven evidence; the calm did not. Since 9 October spreads went to 3.48 on 5 November and printed 3.23 on 13 November, the latest print (ICE BofA via FRED). The miss stands.
Read the note: The Buyers Go Home.; the vanishing-bid thesis
MissedHY OASHeld Out for the IPOs, 9 Jun2.78 to 3.23Open
High-yield spreads hold 2.70 to 3.00% through the AI-equity selloff: a discipline trade, not a credit event. The band held through the June selloff; it broke in late September on rates and went through the tell on 1 October with the Nasdaq at a record. Missed on the level. Since 9 October spreads went to 3.48 on 5 November and printed 3.23 on 13 November, the latest print (ICE BofA via FRED). The miss stands.
Read the note: Held Out for the IPOs; the AI valuation and IPO read
MissedHY OASThe Floor Held. Again., 10 Jun2.78 to 3.23Open
High-yield spreads stay pinned 2.70 to 3.00%: the cross-check that the equity pressure is sector-local. It was, until it was not: 3.24 on 1 October with equities at highs is the credit channel opening on its own, which is the growth path's trigger, not the equity one. Since 9 October spreads went to 3.48 on 5 November and printed 3.23 on 13 November, the latest print (ICE BofA via FRED). The miss stands.
Read the note: The Floor Held. Again.; the post-CPI rate-floor verdict
Rotated two-branchHY OASThe Tide Line, 14 Sep2.70 to 3.15Resolved
Drifts, 2.60 to 2.90. It drifted to 2.68 on 22 September, then 56bp in seven sessions to 3.24 on 1 October, through the condition the note published for the growth path and through the tell the same note named in its scenario map. The base case failed on this leg and the note's own Path B trigger fired, which is what the map was for. Scored Rotated: the stated trigger fired and the mapped growth path took the weight, the same treatment as the 29 September tell row.
Read the note: The Tide Line; the reweight, scored on the print
MissedCredit, the equity sell-offThe Committee Held. The Long End Did Not., 30 Oct3.14 to 3.44Resolved
Read the equity sell-off as an equity and duration event so far, not a credit event, with Thursday's spread print the first test. High-yield spreads printed 3.26 on 29 October and 3.44 on 30 October (ICE BofA via FRED). The reading failed its own first test: missed, logged in The Barrel Fell. The Core Did Not.
Read the note: The Committee Held. The Long End Did Not.; the FOMC, scored; scored in The Barrel Fell. The Core Did Not.
Commodities14 scored: 8 held, 2 partial, 1 rotated, 3 missed; 79% held or better
HeldBrentSix Pillars, 1 Junto ~105 to 92.44 (tape)Open
Brent trades a 90 to 100 range while the Iran war premium persists. It fell out of the range on the ceasefire, returned as it lapsed, ran to 106 on the Saudi pipeline shutdown, dipped under 96 as the pipeline restarted and closed 9 October near 105 on the tape, products leading on reports of US strike preparations. Through the top of the band by about five dollars, in the spirit of the call. Re-scored on the current tape: front-month Brent ran to 117.64 on 30 October, the day the December contract expired, then January Brent fell back into the band, 92.44 at the 16 November settle. Inside 90 to 100 at this mark: held; it was partial at the 9 October one.
Read the note: Six Pillars; the structural-regime read
RotatedBrentThe Buyers Go Home., 16 Jun85 to 78 to ~105 (tape)Resolved
Brent eases on the ceasefire while the long-end floor stays: energy relief lands in oil, not in duration. The relief held until the ceasefire expired and Brent recovered.
Read the note: The Buyers Go Home.; the vanishing-bid thesis
HeldBrentThe Floor Held. Again., 10 Junto ~105 to 92.44 (tape)Open
Brent stays rangebound but elevated on the unresolved Iran conflict. Elevated still: 106 at the September peak, near 105 at the 9 October close with the strait contested again. 92.44 at the 16 November settle: still above the pre-war range, elevated, and inside the 90 to 100 band.
Read the note: The Floor Held. Again.; the post-CPI rate-floor verdict
HeldBrentThe Shock Writes. The Committee Waits., 1 Sep90.5 to 92.44Open
The strait as a ratchet, not a panic; the pain trade is de-escalation; the 98th-percentile crude long is right until it is not. Brent went 90.49 to 106 without a gap day, the long grew and was right, then Saudi Arabia restored the East-West pipeline and the pain trade arrived: 98.4, and the long is the one paying. 92.44 at the 16 November settle after a run to 117.64 on 30 October; tactical, the pain trade the note named has arrived twice.
Read the note: The Shock Writes. The Committee Waits.; the strait as a ratchet, not a panic
MissedBrentThe Tide Line, 14 Sep104.6 to 92.44Open
100 to 110, products lead, the crack wide. Held the band for two weeks to 106, slipped under it as the pipeline restarted, and closed 9 October inside it at about 105 on the tape, the December contract at 104.72. Inside the band on the as-of date; the disarm legs the note registered, Brent under 95 with the margin through 55, a pipeline restart and a lane accord, stand at one delivered and three not. Re-scored on the current tape: the band broke both ways, through 110 to 117.64 on 30 October, then under 100 from 4 November, 92.44 at the 16 November settle. Missed at this mark; held at the 9 October one.
Read the note: The Tide Line; the reweight, scored on the print
Branch resolved two-branchGoldTen Dollars Offered. One Accepted., 20 Aug4523 to 4195; 2Y +61bp vs 30Y +37bpResolved
Registered both branches in advance: sustained trade above 4,449 alongside enlarged buybacks is the fiscal read compounding; a return below it while the two-year leads yields higher is the one combination that would argue the dollar's hawkish case is real. Gold ran to 4,680 on 24 August, closed back under the line on 1 September and has closed below it on every session since 4 September, 4,195 at the 9 October close, while the two-year rose 61bp from the 20 August settle against 37bp on the thirty-year. The dollar branch fired, and what it argued for arrived: a unanimous rise on 16 September. Branch resolved, the dollar case, as the 13 October Brief scores it.
Read the note: Ten Dollars Offered. One Accepted.; the issuer's bid as signal, not flow; scored in Gold Lost the Line. The Dollar Kept the Case.
MissedGoldSix Pillars, 1 Jun4485 to 3856Open
Gold consolidates in a 4,400 to 4,600 range. It drifted below the band on rising real yields, recovered into it, ran to 4,680 in late August, then fell through the floor of the band as the real ten-year went from 2.55 to 2.90: 4,195 on 9 October, 4.7% under the band. Marked to 16 November at 3,856 on the desk feed, further under the band. The miss stands.
Read the note: Six Pillars; the structural-regime read
Missedscoring noteGoldHeld Out for the IPOs, 9 Jun4222 to 3856Open
Scoring note. Missed on price: gold fell 8.7% against a neutral call. The fall came from rates and the dollar rather than the AI-equity story, so the thesis itself had a case for Held; we score on price.
Gold trades neutral: no clear push from the AI-equity story either way. Rangey since, a record in August and within one per cent of the publish level at the 9 October close, on rates rather than on equities. Re-scored on the current tape: 3,856 at the 16 November close, 8.7% under the publish level, on real yields and the dollar rather than on equities. A fall that size is not neutral at the mark: missed; it was held at the 9 October mark.
Read the note: Held Out for the IPOs; the AI valuation and IPO read
PartialGoldThe Floor Held. Again., 10 Jun4047 to 3856Open
Gold consolidates after its post-print unwind, then firms from 4,047 as the fiscal hedge reasserts. It firmed to 4,680 and has given nearly all of it back to real yields; about 150 dollars above the base at the 9 October close. The firming the note named came, to 4,680 in August, and has now been given back in full: 3,856 at the 16 November close, under the 4,047 base. Partial: delivered, then materially given back.
Read the note: The Floor Held. Again.; the post-CPI rate-floor verdict
PartialGoldThe Buyers Go Home., 16 Jun4331 to 3856Open
Gold consolidates at elevated levels as the fiscal-and-bid hedge, not the war hedge. It held and pushed to records into August, then fell 12% from the peak as real yields rose 35bp in three weeks. Elevated by any longer measure, and 3% under the publish level. Marked to 16 November at 3,856, 11% under the publish level. Partial stands.
Read the note: The Buyers Go Home.; the vanishing-bid thesis
HeldGoldThe War Is Over. The Floor Isn't., 19 Jun4188 to 3856Open
Gold lower on the dollar bid: with the war premium gone, gold trades the dollar. It went the other way first, to a 4,680 record in August while the dollar softened, and this page scored it missed at the 28 August mark; it came back through the publish level in September as the dollar went to 101 and was scored held at the 2 October mark. At the 9 October close it sits seven dollars above the publish level with the dollar at 102.2, a fraction offside, and the symmetric rule scores it as it finds it: missed, with the path stated in full. Re-scored on the current tape: with the dollar index at 103.59 on 16 November, gold closed 3,856, 332 dollars under the publish level. Lower on the dollar bid: held at this mark; it was missed at the 9 October one.
Read the note: The War Is Over. The Floor Isn't.; the post-ceasefire floor, and gold on the dollar
HeldGoldThe Tide Line, 14 Sep4348 to 3856Open
Consolidates under 4,449 with the two-year leading. Under it throughout, 4,195 at the 9 October close, and the two-year led every session that mattered. Under it throughout, 3,856 at the 16 November close.
Read the note: The Tide Line; the reweight, scored on the print
HeldGoldThe High-Water Mark, 18 Augnet long 243k to 210kOpen
The inflation hedge is crowding: a hedge the crowd already owns pays worse on the event. Speculative net length kept building to 243,334 contracts on 25 August and has since unwound to 210,335 on 6 October, the lowest of the eight weekly reports since 18 August, while the price fell about seven per cent from the 20 August settle. The crowd owned it, and it paid worse. Scored Held in the 13 October Brief. Not re-marked: the positioning series was not refreshed for this preview.
Read the note: The High-Water Mark; the positioning read; scored in Gold Lost the Line. The Dollar Kept the Case.
Held two-branchGold, the controlThe Price of Duration, 6 Oct4141 to 3856 vs 4449Open
Registered gold as the control: gold under 4,449 confirms the reading; gold retaking 4,449 with breakevens rising would say the market had started reading credibility, and the desk would reverse on it. Gold went from 4,141 on 5 October to 4,195 at the 9 October close, still more than 250 dollars under the line, with the ten-year breakeven at 2.33 from 2.36. Neither leg of the reversal is close. Scored Held in the 13 October Brief. Still under the line: 3,856 at the 16 November close with the ten-year breakeven at 2.20; held again in the 11 November Premium.
Read the note: The Price of Duration; the regime named, the range redrawn; scored in Gold Lost the Line. The Dollar Kept the Case.
Trigger not metBrent, the shock pathThe Price of Duration, 6 Oct104.72 to 117.64; margin near 49Resolved
The shock path triggers on Brent through 110 on the December contract with products leading and the refining margin above 70, or the breakeven through 2.50 with the thirty-year through 5.80 in the same week. Brent went through 110 to 116.7 on 23 October but products did not lead; the breakeven peaked at 2.38. Not met when the map was retired on 11 November. A condition for switching paths: shown, not scored.
Read the note: The Price of Duration; the regime named, the range redrawn, the reweight on the fired tell; scored in The Barrel Fell. The Core Did Not.; not scored
Equities6 scored: 3 held, 1 partial, 2 missed; 67% held or better
MissedSemis (SMH)Six Pillars, 1 Jun608 to 461.9Open
Semiconductors keep leading the tape higher on the AI-infrastructure build. They rolled over in June, fell to 542 in early September, led again into early October, then fell 4.3% in the week to 9 October to 603, under the publish level, while the S&P sat 2.8% above its own. Scored on the current tape, as the symmetric rule requires: not leading at the 9 October mark; it was held at the 2 October one. Marked to 16 November at 461.9, 24% under the publish level. The miss stands.
Read the note: Six Pillars; the structural-regime read
MissedS&P 500Six Pillars, 1 Jun7600 to 7417Open
The S&P 500 grinds higher on ample liquidity. Higher: 2.8% above the publish level at the 9 October close, with a record close on 6 October, the ten-year at 5.24 overhead and credit a few basis points through the desk's tell. Re-scored on the current tape: 7,417 at the 16 November close, 2.4% under the publish level, after a low of 7,354 on 5 November. Not higher at this mark: missed; it was held at the 9 October one.
Read the note: Six Pillars; the structural-regime read
HeldNasdaqHeld Out for the IPOs, 9 Jun25930 to 24510Open
The Nasdaq goes range-bound to 5 to 10% lower as the AI valuation premium reprices. The thesis-direction drop came early (about 7% into the 10 June low) then reversed: open, currently offside by 5.5%, with the stated invalidation (HY OAS through 3.50) not fired at 3.15. Re-scored: the Nasdaq fell from its October highs to 24,315 on 5 November and closed 24,510 on 16 November, 5.5% under the publish level and inside the 5 to 10% lower the note wrote. The invalidation, high-yield spreads through 3.50, did not fire (peak 3.48). Held at this mark; early at the 9 October one.
Read the note: Held Out for the IPOs; the AI valuation and IPO read
HeldNasdaq / AIThe Floor Held. Again., 10 Jun25170 to 24510Open
The AI complex stays a range-bound, relative laggard. A forward-guidance call on the AI valuation reset: the tape has run against it since, open and currently offside by 8.7%, pending the stated invalidation. Re-scored: 24,510 at the 16 November close, 2.6% under the publish level while the S&P 500 is 2.1% above its own 10 June level. Range-bound and the relative laggard at this mark: held; early at the 9 October one.
Read the note: The Floor Held. Again.; the post-CPI rate-floor verdict
HeldSemis (SMH)Held Out for the IPOs, 9 Jun591 to 461.9Open
Semiconductors underperform quality mega-caps as capex discipline bites. They did into September, outran the index into early October, then gave it back: since 9 June SMH is up 2.1% against 5.7% for the S&P at the 9 October close. Scored held on the current tape, as the symmetric rule requires; it was missed at the 2 October mark. Marked to 16 November: SMH down 21.8% since 9 June against the S&P 500 up 0.4%.
Read the note: Held Out for the IPOs; the AI valuation and IPO read
PartialS&P 500The Tide Line, 14 Sep7657 to 7417Open
Range-bound, rates a ceiling; energy over the consumer complex. 7,552 to 7,819 over four weeks, 2.0% above where it started at the 9 October close, with the record close of 6 October made in the week the long end set its high. Re-scored: 7,417 at the 16 November close, 3.1% under where it started; rates stayed a ceiling. The second half did not hold: since 14 September the energy sector fund is down 1.3% and the consumer discretionary fund up 4.7%. Half of a compound claim: partial; held at the 9 October mark.
Read the note: The Tide Line; the reweight, scored on the print
Process log
We log our own lateness here
Separately from market calls, so you can see both. These rows measure timeliness, not a view on the market, and they are not in the call count.
LateThe deliveryThe Tide Line, 14 Sepowed 17 Sep to scored 28 SepResolved
The desk pre-committed in print to score the four tests above on the 17 September settle. They were scored on 28 September, seven sessions late, the second consecutive late delivery on a dated pre-commitment and the first to go unacknowledged at the time. Logged at the weight of a missed level. The fix is structural and in the 29 September note: publish what has settled, register what has not.
Read the note: The Tide Line; the reweight, scored on the print
LateThe delivery, 2 OctoberTwelve to Nothing, 29 Sepowed 2 Oct to scored 5 OctResolved
The payroll test was owed on the 2 October settle under the note's own structural rule, publish what has settled. The scoring Brief went out on Monday 5 October, one session later, the third note in a row to arrive after the settle it scores. Logged at the weight of a missed level, after the hits, as the 5 October Brief logs it.
Read the note: Twelve to Nothing; the FOMC tests scored; the curve went further
LateThe delivery, 8 OctoberDuration Cleared. The Crowd Did Not., 12 Octowed 9 Oct to published 12 OctResolved
Registered 6 October, owed on the 8 October settle. Under the standard set on 29 September, publish what has settled, the scoring note was due on Friday 9 October; it was scheduled and not produced, and went out on Monday 12 October, one full session late. The fourth of the desk's last five notes to arrive after the settle it was owed on. Logged at full weight.
Read the note: Duration Cleared. The Crowd Did Not.; the retest, scored
LateThe delivery, 23 October and the Record refreshThe Committee Held. The Long End Did Not., 30 Octowed 23 Oct, published 30 Oct; Record owed 19 Oct, published 29 OctResolved
The fortnight scorecard was owed on the 23 October settle and published on 30 October, four sessions late; the Record refresh registered on 15 October for the 19th was published on 29 October. Logged outside the call count.
Read the note: The Committee Held. The Long End Did Not.; the FOMC, scored
LateThe second breach, 2 NovemberThe Barrel Fell. The Core Did Not., 11 Novprinted 2 Nov, recorded 11 NovResolved
The second close through the thirty-year range floor, 5.28 on 2 November, was recorded seven sessions after it printed, and the Record had not been refreshed since 29 October. Logged outside the call count.
Read the note: The Barrel Fell. The Core Did Not.; the map redrawn to the December meetings
Methodologydefinitions, sources and rules
Verdicts
- Held: the claim is true at the mark.
- Branch resolved: a two-branch call where the tape picked a branch the note set out in advance. Counted as held, including when the desk had named the other branch as its base case.
- Partial: half of a compound claim held, or the move the call named was delivered and then materially given back. Counted inside held or better and shown separately.
- Rotated: the note's stated invalidation or trigger fired and a mapped scenario from the same note took over. Counted inside held or better.
- Ran, then closed: a closed call that made at least 100 pips, 15 basis points or 1% before its invalidation fired. None at this mark.
- Early and Ambiguous: in the denominator, not in the numerator.
- Missed: the claim is false at the mark and was not delivered on the way to it.
- Trigger not met: a condition for switching paths that did not fire. A condition is not a forecast, so it is shown and not scored.
- New: registered, not yet scored.
The headline
Held or better = (held + partial + rotated) ÷ every scored call, misses, early and ambiguous rows included in the denominator. At this mark: (52 + 12 + 3) ÷ 92 = 72.8%, shown as 73%. Held alone: 52 ÷ 92 = 56.5%. Missed: 23 ÷ 92 = 25.0%.
Status and horizons
Open: the scenario is still in play and the as-of mark is a waypoint. Resolved: a stated trigger fired or the stated horizon passed, and the row is frozen. A call is marked while its thesis remains valid, unless its stated invalidation fires or a later note explicitly closes it. Where a note gave a tactical horizon, the row shows it.
Levels
US Treasury yields: the Treasury's daily par yield curve. FX, commodities and equities: end-of-day closes on the desk's feed; Brent is the front-month tape rather than a named contract, which is why its rows say tape. Entry is the published level for each call; where a note's wording was to sell rallies or buy dips rather than enter at the market, the record checks that price traded through the entry after publication and before any invalidation. Every open row is marked to 16 November 2026. High-yield credit's official print lags a session, so the credit rows carry the 13 November print of 3.23.
Changes at this mark
17 November 2026: every open row re-marked from the 9 October close to the 16 November close. The rows below changed verdict on the current tape, in both directions, under the symmetric rule. This refresh applies Pardip's 17 November decisions: the 15 October dollar stance is scored Early, the 2.50 breakeven line is merged into one row, and gold's Held Out for the IPOs row is Missed with a scoring note.
Re-scored, US 30-year, The Price of Duration, 6 Oct: Held to Missed. Range 5.30 to 5.80 breached 22 Oct (5.29); scored missed by the 30 Oct Brief and 11 Nov Premium
Re-scored, 2s30s, The Tide Line, 14 Sep: Partial to Held. Flattens further: 69bp entry, 63bp at mark (flatter)
Re-scored, 10-year breakeven, The Tide Line, 14 Sep: Held to Missed. Band 2.30 to 2.45 broken low (2.20 at mark)
Re-scored, Breakevens, the discriminator, Twelve to Nothing, 29 Sep: New to Held. Registered New; line 2.50 never threatened (peak 2.38). Merged with the 6 Oct Price of Duration 2.50 line, one scored row.
Re-scored, Credit, the conversion, The Price of Duration, 6 Oct: New to Trigger not met. Path B conversion not met; the 11 Nov Premium retired the map
Re-scored, Brent, Six Pillars, 1 Jun: Partial to Held. Range 90 to 100: inside at 92.44
Re-scored, Brent, The Tide Line, 14 Sep: Held to Missed. Band 100 to 110: 92.44 at mark
Re-scored, Gold, Held Out for the IPOs, 9 Jun: Held to Missed. Gold neutral: 8.7% under entry. Missed on price, with a scoring note: the thesis had a case for Held.
Re-scored, Gold, The Floor Held. Again., 10 Jun: Held to Partial. Firmed to 4,680 then gave it back below the 4,047 base
Re-scored, Gold, The War Is Over. The Floor Isn't., 19 Jun: Missed to Held. Gold lower on the dollar bid: 3,856 vs 4,188 entry, dollar index 103.59
Re-scored, S&P 500, Six Pillars, 1 Jun: Held to Missed. Grinds higher: 7,417 vs 7,600 entry
Re-scored, Nasdaq, Held Out for the IPOs, 9 Jun: Early to Held. 5 to 10% lower: -5.5% at mark
Re-scored, Nasdaq / AI, The Floor Held. Again., 10 Jun: Early to Held. Relative laggard: Nasdaq -2.6% vs S&P +2.1% since 10 Jun
Re-scored, S&P 500, The Tide Line, 14 Sep: Held to Partial. Energy did not beat the consumer complex since 14 Sep
Added: 10-year breakeven, the band, The Price of Duration, 6 Oct (Missed); Term premium, The Price of Duration, 6 Oct (Missed); US 2-year, The Price of Duration, 6 Oct (Missed); Duration clears at a price, The Price of Duration, 6 Oct (Held); US 30-year, The Barrel Fell. The Core Did Not., 11 Nov (New); The queue across the long end, Duration Cleared. The Crowd Did Not., 12 Oct (Missed); The CPI test, Duration Cleared. The Crowd Did Not., 12 Oct (Held); The 4.80 line through the CPI, Twelve to Nothing, 29 Sep (Held); DXY, The Price of Duration, 6 Oct (Partial); The dollar, the tactical stance, The Print Was Hot. The Tape Sold It., 15 Oct (Early); EUR/USD, the positioning caveat, The Price of Duration, 6 Oct (Held); Credit, the equity sell-off, The Committee Held. The Long End Did Not., 30 Oct (Missed); Brent, the shock path, The Price of Duration, 6 Oct (Trigger not met). Each was registered or scored in a note published between 12 October and 11 November. The 6 October 2.50 breakeven line from The Price of Duration is merged into the 29 September discriminator row and is not counted separately.
Process log: two rows added (the 23 October delivery and Record refresh; the 2 November second breach recorded on 11 November). Logged as Late, as confirmed.
Free from the desk
Get the next call before the data.
Every Brief and Analysis as a teaser, dated before the print and scored here afterwards. Premium unlocks the full scenario maps, levels and invalidation criteria.
This page is editorial commentary on observable market developments and a record of published views. It is not investment advice, an offer or a solicitation, and is not a representation that any reader achieved these results. Past performance is not indicative of future results. We read the data. We call the paths.